


Tilapia Market
Tilapia Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Tilapia Market Size and Trend Analysis
How Fast Is the Tilapia Market Growing?
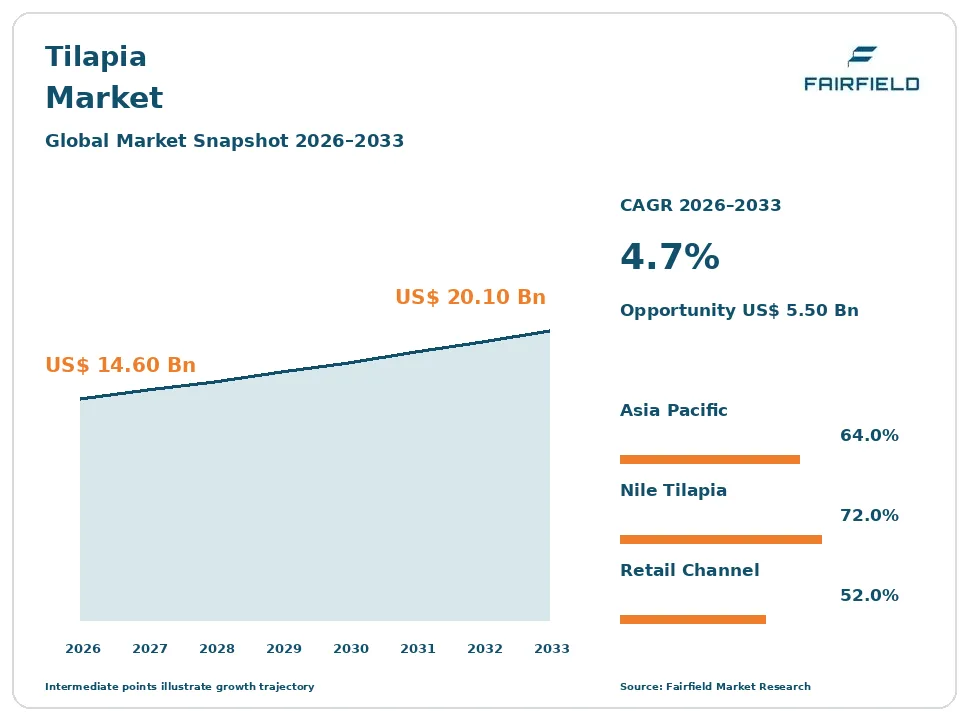
The global tilapia market size is expected to be valued at US$ 14.60 billion in 2026 and projected to reach US$ 20.10 billion by 2033, growing at a CAGR of 4.7% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 4.2%, supported by rising demand for affordable protein and steady expansion of fish farming in Asia Pacific, Latin America, and Middle East & Africa. Tilapia is one of the most widely farmed fish in the world, valued for its mild taste, fast growth, and ability to live in fresh and brackish water. Three factors now drive growth: global demand for low-cost, healthy protein, the expansion of aquaculture as wild fish catches stay flat, and growing exports of frozen fillets and fresh fish to the United States and Europe. The market is shifting toward improved breeds of Nile tilapia, certified sustainable farms, and value-added products such as ready-to-cook portions. Trade policy is a growing factor in seafood trade, as shown by 2025 tariffs that disrupted exports from Brazil to the United States.
Key Report Takeaways
- By Species: Nile Tilapia held 72.0% share in 2026, while Blue Tilapia is projected to expand at a 5.3% CAGR through 2033, driven by its cold tolerance and use in hybrid breeding programs.
- By Product Form: Frozen held 48.0% share in 2026, while Fresh and Chilled is projected to expand at a 5.6% CAGR through 2033, driven by fast air and road delivery to nearby markets.
- By Distribution Channel: Retail held 52.0% share in 2026, while Food Service is projected to expand at a 5.4% CAGR through 2033, driven by restaurants and quick-service chains adding fish dishes.
- By Region: Asia Pacific held 64.0% share in 2026, while Latin America is projected to expand at a 6.4% CAGR through 2033, driven by fast production growth in Brazil, Colombia, and Mexico.
Global Tilapia Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Demand for affordable, healthy protein | High | Global | Long term (≥4 years) |
| Expansion of aquaculture production | High | Asia Pacific, Latin America, Middle East & Africa | Medium term (2-4 years) |
Two drivers carry the strongest influence on tilapia demand during the forecast period.
Protein Demand Is Driving the Tilapia Market
Demand for affordable, healthy protein is the strongest driver of the tilapia market. Tilapia offers lean protein at a lower price than many other fish and meats.
The mechanism is population and income growth. The world population is rising, and growing middle classes in Asia Pacific, Latin America, and Middle East & Africa are eating more animal protein. Tilapia is low in fat and calories, high in protein, and has a mild taste that suits many cuisines. It is cheaper than salmon, shrimp, and many beef and pork cuts, making it popular with budget-conscious families, schools, and food service operators. Health guidelines in many countries recommend eating fish at least twice a week. Tilapia can be sold whole, as frozen fillets, or in ready meals, giving it wide appeal. These factors support steady consumption growth.
Aquaculture Expansion Is Expanding the Tilapia Market
The expansion of aquaculture is expanding the tilapia market. Fish farming is growing faster than wild fishing.
The cause is limited wild fish stocks and the efficiency of farming. Wild catches have stayed flat for years, so most new seafood supply comes from farmed fish. Tilapia grows fast, tolerates crowded conditions and lower water quality, and eats mostly plant-based feed, which keeps costs low. China, Indonesia, Egypt, Brazil, Bangladesh, and the Philippines are major producers. Brazil’s farmed fish output passed 1 million tonnes in 2025, with tilapia making up about 70%. Improved breeds, better feed, vaccines, and cage farming in lakes and reservoirs raise yields. Large feed companies now make special tilapia feeds that improve growth and reduce waste. These trends grow supply and lower prices.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Disease outbreaks and environmental concerns | High | Asia Pacific, Latin America | Medium term (2-4 years) |
| Trade barriers and price competition | Medium | Global | Short term (≤2 years) |
Two restraints limit how quickly the tilapia market grows.
Disease and Environmental Risks Slow the Tilapia Market
Disease outbreaks and environmental concerns slow the tilapia market. Large farms can suffer heavy losses from fish diseases.
The specific causes are intensive farming and climate pressures. Tilapia lake virus and bacterial diseases such as streptococcus have caused major deaths on farms in Asia Pacific, Latin America, and Middle East & Africa, including Egypt. Crowded ponds and cages spread disease quickly. Heat waves and droughts lower water quality and oxygen levels. Waste from fish farms can pollute lakes and rivers, leading to stricter rules and permit limits. Escaped tilapia can harm local fish and wildlife in some regions. Feed prices for soy and corn affect farm profits. Vaccines and better farm management help but add costs for small farmers. These factors raise costs and production risks.
Trade Barriers Restrict the Tilapia Market
Trade barriers and price competition restrict the tilapia market. Global seafood trade is exposed to tariffs and policy changes.
The underlying causes are trade disputes and low-cost competition. The United States has placed high tariffs on imports from China, the largest tilapia exporter, and in 2025 it raised tariffs on goods from Brazil to 50%, threatening Brazilian tilapia exports. In January 2026, Brazil allowed tilapia imports from Vietnam with a tariff, angering local farmers. Low prices from large exporters squeeze margins for smaller producers in many countries. Consumer concerns about farming practices, antibiotics, and food safety also affect demand in some markets. Currency swings in exporting countries also change prices quickly. Retailers in Europe may favor other white fish such as pangasius, cod, or pollock. These factors make trade flows uncertain.
Market Opportunities
Value-Added Products Open a Premium Revenue Pool
Value-added products open a premium revenue pool in the tilapia market. Consumers want convenient, ready-to-cook fish.
Processors that invest in product development can capture this opportunity. Marinated fillets, breaded portions, fish burgers, smoked tilapia, and ready meals sell at higher prices than whole fish. Skin, scales, and by-products can be used for collagen, gelatin, fish meal, leather, and even burn dressings in medicine. Retailers and restaurant chains want consistent, easy-to-cook products with clear labels. Certified sustainable tilapia from farms with Aquaculture Stewardship Council or Best Aquaculture Practices labels earns premium prices. These products improve margins for farms and processors. Online grocery and meal-kit companies are also new outlets for prepared tilapia. Processors that build strong brands can reduce dependence on low-price commodity sales.
Recirculating and Domestic Farming Create a Local Supply Revenue Pool
Recirculating systems and domestic farming create a local supply revenue pool in the tilapia market. Many countries want to produce more fish at home.
Technology suppliers and local farmers can capture this opportunity. Recirculating aquaculture systems let farms grow tilapia indoors near cities with much less water use and lower disease risk. Countries such as Saudi Arabia, the United Arab Emirates, Ghana, Kenya, and Nigeria are investing in fish farming to improve food security. Tariffs on imports in the United States and other countries encourage domestic production and local investment. Local supply means fresher fish and lower transport costs. Development banks and aid programs fund cage farming in African lakes, creating jobs and improving nutrition. Solar-powered aeration and feeding systems help small farms raise output.
Segment Analysis
By Species: Nile Tilapia Leads While Blue Tilapia Grows Fastest
Nile Tilapia held 72.0% share in 2026. Nile tilapia is the most widely farmed species because it grows fast, converts feed efficiently, and adapts to many farming systems. Improved strains, such as GIFT tilapia developed by WorldFish, have raised growth rates across Asia Pacific and Middle East & Africa. Regal Springs and Charoen Pokphand Foods farm large volumes.
Blue Tilapia is the fastest-growing species, expanding at a 5.3% CAGR through 2033. Blue tilapia tolerates much colder water than Nile tilapia, making it useful in cooler regions and in hybrid breeding programs that produce red tilapia and all-male stocks. Mozambique and other species serve smaller local niches. Breeding companies such as GenoMar sell improved fingerlings to farms in many countries. For the market, blue tilapia growth widens farming areas.
By Product Form: Frozen Leads While Fresh and Chilled Grows Fastest
Frozen held 48.0% share in 2026. Frozen fillets and whole frozen fish are the main traded forms, shipped from China, Indonesia, and Vietnam to the United States, Mexico, and other importers. Freezing allows long storage and low-cost shipping in containers over long distances.
Fresh and Chilled is the fastest-growing product form, expanding at a 5.6% CAGR through 2033. Fresh fillets from Brazil, Colombia, Honduras, and Costa Rica reach the United States by air within days, and local fresh fish markets are growing in many countries. Fresh tilapia sells at higher prices than frozen, and buyers value its better texture. Live fish markets remain important in China and parts of Asia Pacific. For the market, fresh growth raises value.
By Distribution Channel: Retail Leads While Food Service Grows Fastest
Retail held 52.0% share in 2026. Supermarkets, hypermarkets, discount stores, fish markets, and online grocers sell tilapia as fillets, whole fish, and ready meals. Low prices make it a staple in many households, and retailers often run promotions on tilapia fillets. Online grocery sales of fish are rising in cities.
Food Service is the fastest-growing distribution channel, expanding at a 5.4% CAGR through 2033. Restaurants, schools, hospitals, and quick-service chains use tilapia in fish tacos, sandwiches, curries, and buffets because it is affordable, mild, and easy to cook. Large food service distributors sign long-term supply contracts with processors and importers. For the market, food service growth adds volume.
Geography Analysis
North America Advances the Tilapia Market Through Imports
North America is a major tilapia consumer market. The United States is one of the largest tilapia importers, buying frozen fillets mainly from China and Indonesia and fresh fillets from Colombia, Honduras, Brazil, and Mexico. Mexico also has large domestic production and consumption, especially during Lent, when fish demand peaks. Canada has growing demand from immigrant communities and health-conscious shoppers. Indoor recirculating farms are being built in some states to supply fresh fish locally. Key barriers include high tariffs and consumer concerns about imported fish. One change shaping the region is shifting import sources.
Europe Builds the Tilapia Market Through Sustainable Imports
Europe is a smaller but growing tilapia market. Germany, the United Kingdom, the Netherlands, Poland, and Spain import tilapia, mostly as frozen fillets, and buyers strongly prefer certified sustainable products with clear origin labels. Some recirculating farms operate in the Netherlands, Belgium, and Germany, supplying fresh fish to nearby cities. Ethnic food markets and food service drive much of the demand. Strict EU food safety rules require careful checks on imports from all countries. Key barriers include competition from other white fish and limited awareness. One opportunity is certified products sold through supermarkets.
Which Region Is Leading the Tilapia Market?
Asia Pacific is leading the tilapia market with a 64.0% share in 2026. China is the largest producer and exporter, with major farms in Hainan, Guangdong, and Guangxi, and Indonesia, the Philippines, Bangladesh, Thailand, and Vietnam are major producers. India is expanding tilapia farming under its national fisheries programs. Hainan Xiangtai Fishery and Charoen Pokphand Foods are leading regional firms. Rising incomes in China and Indonesia support domestic consumption, and Chinese exporters are seeking new buyers outside the United States. Key barriers include disease and tariffs. One change shaping the region is export diversification.
Which Region Is Growing Fastest in the Tilapia Market?
Latin America is growing fastest in the tilapia market at a 6.4% CAGR through 2033. Brazil produced more than 700,000 tonnes of tilapia in 2025, led by cooperatives such as Copacol and C.Vale, and it is expanding exports. Colombia, Honduras, Mexico, and Costa Rica export fresh fillets to the United States. Large reservoirs in Brazil provide space for cage farming, and feed is cheap thanks to local soy and corn. Domestic consumption in Brazil is also rising quickly. Key barriers include tariffs and import competition. One opportunity is new export markets in Europe, Asia Pacific, and Middle East & Africa.
Middle East & Africa Expands the Tilapia Market Through Food Security Programs
Middle East & Africa is a growing tilapia market. Egypt is one of the world’s largest tilapia producers, mostly for local consumption in the Nile Delta region, and Ghana, Kenya, Uganda, Zimbabwe, and Nigeria are expanding cage farming in large lakes. Saudi Arabia and Israel use advanced farming systems that save water in dry climates. Governments across the region see fish farming as a way to improve food security and create jobs. Lake Volta in Ghana and Lake Kariba in Zimbabwe host large cage farms. Key barriers include feed costs and limited cold chains. One opportunity is local farming.
Competitive Landscape
The tilapia market is fragmented, with thousands of small and medium farms alongside large integrated companies. Regal Springs, which farms in Indonesia, Mexico, and Honduras, Charoen Pokphand Foods, Hainan Xiangtai Fishery, Copacol, C.Vale, Aquafinca, Lake Harvest, and Tropo Farms are leading producers, while GenoMar and WorldFish supply improved genetics.
Companies compete mainly on cost, quality, food safety, certification, product range, logistics, and access to export markets. Large integrated firms that control breeding, feed, farming, and processing have lower costs and better quality control. Certification by the Aquaculture Stewardship Council and Best Aquaculture Practices helps exporters win contracts with large retailers. Smaller and family farms usually sell through cooperatives, traders, or local fish markets. Trade policy changes can quickly shift which countries win export orders, rewarding flexible producers.
Strategic moves show how competition is changing. In August 2025, a 50% tariff on Brazilian goods in the United States threatened tilapia exports after a 52% rise in the first half of the year. In January 2026, Brazil lifted its ban on tilapia imports from Vietnam with a 22% tariff. In March 2026, data showed Brazil’s farmed fish output passed 1 million tonnes in 2025. These moves show competition shaped by trade policy, scale, and shifting supply sources.
Three themes shape vendor strategy. First, companies are diversifying export markets to reduce tariff risk. Second, they are adding value-added products with higher margins. Third, they are seeking sustainability certifications.
Tilapia Market Industry Leaders
- Regal Springs
- Charoen Pokphand Foods
- Hainan Xiangtai Fishery
- Copacol
- Aquafinca
Recent Industry Developments
- March 2026: Industry data showed Brazil’s farmed fish production passed 1 million tonnes in 2025, with tilapia reaching about 707,500 tonnes - confirms Brazil as a fast-growing tilapia producer.
- January 2026: Brazil lifted its ban on tilapia imports from Vietnam, with a 22% tariff applied - increases competition for local farmers.
- August 2025: A 50% tariff on Brazilian goods in the United States threatened to halt tilapia exports after a 52% rise in the first half of 2025 - shows trade risk in seafood trade.
Companies Covered in the Report
- Regal Springs
- Charoen Pokphand Foods
- Hainan Xiangtai Fishery
- Copacol
- C.Vale
- Aquafinca
- Lake Harvest
- Tropo Farms
- Nam Sai Farms
- GenoMar
- Pacific Seafood Group
- High Liner Foods
Tilapia Market Report Scope
This report covers tilapia, including Nile, blue, Mozambique, and other species, sold as frozen, fresh and chilled, and processed products through retail and food service channels, for food, feed, pet food, and other uses. It includes farmed tilapia from ponds, cages, and recirculating systems. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
Species
- Nile Tilapia
- Blue Tilapia
- Mozambique Tilapia
- Others
Product Form
- Frozen
- Fresh and Chilled
- Processed
Distribution Channel
- Retail
- Food Service
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the tilapia market in 2026?
The tilapia market is valued at US$ 14.60 billion in 2026, led by Nile tilapia and Asia Pacific production.
What is the tilapia market forecast to 2033?
The market is projected to reach US$ 20.10 billion by 2033, growing at a 4.7% CAGR and adding US$ 5.50 billion.
Which product form is growing fastest in the tilapia market?
Fresh and chilled tilapia is growing fastest at a 5.6% CAGR through 2033, driven by fast delivery to nearby markets.
Which region is growing fastest in the tilapia market?
Latin America is growing fastest at a 6.4% CAGR through 2033, driven by rapid production growth in Brazil, Colombia, and Mexico.
Which region holds the largest tilapia market share?
Asia Pacific holds the largest share at 64.0% in 2026, supported by large-scale production in China and Indonesia.
1. Executive Summary
1.1. Global Tilapia Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Protein Demand Is Driving the Tilapia Market
2.3.1.2. Aquaculture Expansion Is Expanding the Tilapia Market
2.3.2. Restraints
2.3.2.1. Disease and Environmental Risks Slow the Tilapia Market
2.3.2.2. Trade Barriers Restrict the Tilapia Market
2.3.3. Market Opportunities
2.3.3.1. Value-Added Products Open a Premium Revenue Pool
2.3.3.2. Recirculating and Domestic Farming Create a Local Supply Revenue Pool
3. Global Tilapia Market Outlook, 2020-2033
3.1. Global Tilapia Market Outlook, by Species, Value (US$ Billion), 2020-2033
3.1.1. Nile Tilapia
3.1.2. Blue Tilapia
3.1.3. Mozambique Tilapia
3.1.4. Others
3.2. Global Tilapia Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
3.2.1. Frozen
3.2.2. Fresh and Chilled
3.2.3. Processed
3.3. Global Tilapia Market Outlook, by Distribution Channel, Value (US$ Billion), 2020-2033
3.3.1. Retail
3.3.2. Food Service
3.4. Global Tilapia Market Outlook, by Region, Value (US$ Billion), 2020-2033
3.4.1. North America
3.4.2. Europe
3.4.3. Asia Pacific
3.4.4. Latin America
3.4.5. Middle East & Africa
4. North America Tilapia Market Outlook, 2020-2033
4.1. North America Tilapia Market Outlook, by Species, Value (US$ Billion), 2020-2033
4.1.1. Nile Tilapia
4.1.2. Blue Tilapia
4.1.3. Mozambique Tilapia
4.1.4. Others
4.2. North America Tilapia Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
4.2.1. Frozen
4.2.2. Fresh and Chilled
4.2.3. Processed
4.3. North America Tilapia Market Outlook, by Distribution Channel, Value (US$ Billion), 2020-2033
4.3.1. Retail
4.3.2. Food Service
4.4. North America Tilapia Market Outlook, by Country, Value (US$ Billion), 2020-2033
4.4.1. United States Tilapia Market Outlook, by Species, 2020-2033
4.4.2. United States Tilapia Market Outlook, by Product Form, 2020-2033
4.4.3. United States Tilapia Market Outlook, by Distribution Channel, 2020-2033
4.4.4. Mexico Tilapia Market Outlook, by Species, 2020-2033
4.4.5. Mexico Tilapia Market Outlook, by Product Form, 2020-2033
4.4.6. Mexico Tilapia Market Outlook, by Distribution Channel, 2020-2033
4.4.7. Canada Tilapia Market Outlook, by Species, 2020-2033
4.4.8. Canada Tilapia Market Outlook, by Product Form, 2020-2033
4.4.9. Canada Tilapia Market Outlook, by Distribution Channel, 2020-2033
5. Europe Tilapia Market Outlook, 2020-2033
5.1. Europe Tilapia Market Outlook, by Species, Value (US$ Billion), 2020-2033
5.1.1. Nile Tilapia
5.1.2. Blue Tilapia
5.1.3. Mozambique Tilapia
5.1.4. Others
5.2. Europe Tilapia Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
5.2.1. Frozen
5.2.2. Fresh and Chilled
5.2.3. Processed
5.3. Europe Tilapia Market Outlook, by Distribution Channel, Value (US$ Billion), 2020-2033
5.3.1. Retail
5.3.2. Food Service
5.4. Europe Tilapia Market Outlook, by Country, Value (US$ Billion), 2020-2033
5.4.1. Germany Tilapia Market Outlook, by Species, 2020-2033
5.4.2. Germany Tilapia Market Outlook, by Product Form, 2020-2033
5.4.3. Germany Tilapia Market Outlook, by Distribution Channel, 2020-2033
5.4.4. United Kingdom Tilapia Market Outlook, by Species, 2020-2033
5.4.5. United Kingdom Tilapia Market Outlook, by Product Form, 2020-2033
5.4.6. United Kingdom Tilapia Market Outlook, by Distribution Channel, 2020-2033
5.4.7. Netherlands Tilapia Market Outlook, by Species, 2020-2033
5.4.8. Netherlands Tilapia Market Outlook, by Product Form, 2020-2033
5.4.9. Netherlands Tilapia Market Outlook, by Distribution Channel, 2020-2033
5.4.10. Poland Tilapia Market Outlook, by Species, 2020-2033
5.4.11. Poland Tilapia Market Outlook, by Product Form, 2020-2033
5.4.12. Poland Tilapia Market Outlook, by Distribution Channel, 2020-2033
5.4.13. Spain Tilapia Market Outlook, by Species, 2020-2033
5.4.14. Spain Tilapia Market Outlook, by Product Form, 2020-2033
5.4.15. Spain Tilapia Market Outlook, by Distribution Channel, 2020-2033
5.4.16. Belgium Tilapia Market Outlook, by Species, 2020-2033
5.4.17. Belgium Tilapia Market Outlook, by Product Form, 2020-2033
5.4.18. Belgium Tilapia Market Outlook, by Distribution Channel, 2020-2033
6. Asia Pacific Tilapia Market Outlook, 2020-2033
6.1. Asia Pacific Tilapia Market Outlook, by Species, Value (US$ Billion), 2020-2033
6.1.1. Nile Tilapia
6.1.2. Blue Tilapia
6.1.3. Mozambique Tilapia
6.1.4. Others
6.2. Asia Pacific Tilapia Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
6.2.1. Frozen
6.2.2. Fresh and Chilled
6.2.3. Processed
6.3. Asia Pacific Tilapia Market Outlook, by Distribution Channel, Value (US$ Billion), 2020-2033
6.3.1. Retail
6.3.2. Food Service
6.4. Asia Pacific Tilapia Market Outlook, by Country, Value (US$ Billion), 2020-2033
6.4.1. China Tilapia Market Outlook, by Species, 2020-2033
6.4.2. China Tilapia Market Outlook, by Product Form, 2020-2033
6.4.3. China Tilapia Market Outlook, by Distribution Channel, 2020-2033
6.4.4. Indonesia Tilapia Market Outlook, by Species, 2020-2033
6.4.5. Indonesia Tilapia Market Outlook, by Product Form, 2020-2033
6.4.6. Indonesia Tilapia Market Outlook, by Distribution Channel, 2020-2033
6.4.7. Philippines Tilapia Market Outlook, by Species, 2020-2033
6.4.8. Philippines Tilapia Market Outlook, by Product Form, 2020-2033
6.4.9. Philippines Tilapia Market Outlook, by Distribution Channel, 2020-2033
6.4.10. Bangladesh Tilapia Market Outlook, by Species, 2020-2033
6.4.11. Bangladesh Tilapia Market Outlook, by Product Form, 2020-2033
6.4.12. Bangladesh Tilapia Market Outlook, by Distribution Channel, 2020-2033
6.4.13. Thailand Tilapia Market Outlook, by Species, 2020-2033
6.4.14. Thailand Tilapia Market Outlook, by Product Form, 2020-2033
6.4.15. Thailand Tilapia Market Outlook, by Distribution Channel, 2020-2033
6.4.16. Vietnam Tilapia Market Outlook, by Species, 2020-2033
6.4.17. Vietnam Tilapia Market Outlook, by Product Form, 2020-2033
6.4.18. Vietnam Tilapia Market Outlook, by Distribution Channel, 2020-2033
6.4.19. India Tilapia Market Outlook, by Species, 2020-2033
6.4.20. India Tilapia Market Outlook, by Product Form, 2020-2033
6.4.21. India Tilapia Market Outlook, by Distribution Channel, 2020-2033
7. Latin America Tilapia Market Outlook, 2020-2033
7.1. Latin America Tilapia Market Outlook, by Species, Value (US$ Billion), 2020-2033
7.1.1. Nile Tilapia
7.1.2. Blue Tilapia
7.1.3. Mozambique Tilapia
7.1.4. Others
7.2. Latin America Tilapia Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
7.2.1. Frozen
7.2.2. Fresh and Chilled
7.2.3. Processed
7.3. Latin America Tilapia Market Outlook, by Distribution Channel, Value (US$ Billion), 2020-2033
7.3.1. Retail
7.3.2. Food Service
7.4. Latin America Tilapia Market Outlook, by Country, Value (US$ Billion), 2020-2033
7.4.1. Brazil Tilapia Market Outlook, by Species, 2020-2033
7.4.2. Brazil Tilapia Market Outlook, by Product Form, 2020-2033
7.4.3. Brazil Tilapia Market Outlook, by Distribution Channel, 2020-2033
7.4.4. Colombia Tilapia Market Outlook, by Species, 2020-2033
7.4.5. Colombia Tilapia Market Outlook, by Product Form, 2020-2033
7.4.6. Colombia Tilapia Market Outlook, by Distribution Channel, 2020-2033
7.4.7. Honduras Tilapia Market Outlook, by Species, 2020-2033
7.4.8. Honduras Tilapia Market Outlook, by Product Form, 2020-2033
7.4.9. Honduras Tilapia Market Outlook, by Distribution Channel, 2020-2033
7.4.10. Mexico Tilapia Market Outlook, by Species, 2020-2033
7.4.11. Mexico Tilapia Market Outlook, by Product Form, 2020-2033
7.4.12. Mexico Tilapia Market Outlook, by Distribution Channel, 2020-2033
7.4.13. Costa Rica Tilapia Market Outlook, by Species, 2020-2033
7.4.14. Costa Rica Tilapia Market Outlook, by Product Form, 2020-2033
7.4.15. Costa Rica Tilapia Market Outlook, by Distribution Channel, 2020-2033
8. Middle East & Africa Tilapia Market Outlook, 2020-2033
8.1. Middle East & Africa Tilapia Market Outlook, by Species, Value (US$ Billion), 2020-2033
8.1.1. Nile Tilapia
8.1.2. Blue Tilapia
8.1.3. Mozambique Tilapia
8.1.4. Others
8.2. Middle East & Africa Tilapia Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
8.2.1. Frozen
8.2.2. Fresh and Chilled
8.2.3. Processed
8.3. Middle East & Africa Tilapia Market Outlook, by Distribution Channel, Value (US$ Billion), 2020-2033
8.3.1. Retail
8.3.2. Food Service
8.4. Middle East & Africa Tilapia Market Outlook, by Country, Value (US$ Billion), 2020-2033
8.4.1. Egypt Tilapia Market Outlook, by Species, 2020-2033
8.4.2. Egypt Tilapia Market Outlook, by Product Form, 2020-2033
8.4.3. Egypt Tilapia Market Outlook, by Distribution Channel, 2020-2033
8.4.4. Kenya Tilapia Market Outlook, by Species, 2020-2033
8.4.5. Kenya Tilapia Market Outlook, by Product Form, 2020-2033
8.4.6. Kenya Tilapia Market Outlook, by Distribution Channel, 2020-2033
8.4.7. Zimbabwe Tilapia Market Outlook, by Species, 2020-2033
8.4.8. Zimbabwe Tilapia Market Outlook, by Product Form, 2020-2033
8.4.9. Zimbabwe Tilapia Market Outlook, by Distribution Channel, 2020-2033
8.4.10. Nigeria Tilapia Market Outlook, by Species, 2020-2033
8.4.11. Nigeria Tilapia Market Outlook, by Product Form, 2020-2033
8.4.12. Nigeria Tilapia Market Outlook, by Distribution Channel, 2020-2033
8.4.13. Saudi Arabia Tilapia Market Outlook, by Species, 2020-2033
8.4.14. Saudi Arabia Tilapia Market Outlook, by Product Form, 2020-2033
8.4.15. Saudi Arabia Tilapia Market Outlook, by Distribution Channel, 2020-2033
8.4.16. Israel Tilapia Market Outlook, by Species, 2020-2033
8.4.17. Israel Tilapia Market Outlook, by Product Form, 2020-2033
8.4.18. Israel Tilapia Market Outlook, by Distribution Channel, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. Regal Springs
9.5.2. Charoen Pokphand Foods
9.5.3. Hainan Xiangtai Fishery
9.5.4. Copacol
9.5.5. C.Vale
9.5.6. Aquafinca
9.5.7. Lake Harvest
9.5.8. Tropo Farms
9.5.9. Nam Sai Farms
9.5.10. GenoMar
9.5.11. Pacific Seafood Group
9.5.12. High Liner Foods
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Species | Nile Tilapia, Blue Tilapia, Mozambique Tilapia, Others |
| Product Form | Frozen, Fresh and Chilled, Processed |
| Distribution Channel | Retail, Food Service |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The tilapia market is valued at US$ 14.60 billion in 2026, led by Nile tilapia and Asia Pacific production.
The market is projected to reach US$ 20.10 billion by 2033, growing at a 4.7% CAGR and adding US$ 5.50 billion.
Fresh and chilled tilapia is growing fastest at a 5.6% CAGR through 2033, driven by fast delivery to nearby markets.
Latin America is growing fastest at a 6.4% CAGR through 2033, driven by rapid production growth in Brazil, Colombia, and Mexico.
Asia Pacific holds the largest share at 64.0% in 2026, supported by large-scale production in China and Indonesia.
Related Reports
Quillaja Extract Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The quillaja extract market is projected to grow from US$397.5 million in 2026 to US$712.7 million by 2033, at an 8.7% CAGR, led by food and vaccine uses.
Organic Tobacco Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The organic tobacco market is projected to grow from US$143.8 million in 2026 to US$193.1 million by 2033, at a 4.3% CAGR, shaped by sourcing and regulation.
Green Cardamom Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Green cardamom market to grow from US$1.6 Bn in 2026 to US$2.3 Bn by 2033 at 5.3% CAGR. Explore forms, grades, applications and regional growth trends.
GMO Testing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
GMO testing market to grow from US$2.2 Bn in 2026 to US$3.6 Bn by 2033 at 7.3% CAGR. Explore testing services, technologies, samples and regional trends.
Glutinous Rice Flour Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Glutinous rice flour market to grow from US$2.4 Bn in 2026 to US$3.5 Bn by 2033 at 5.5% CAGR. Explore products, milling, applications and regions.
Oat Milk Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Oat milk market to reach US$ 13.72 billion by 2033 at a 16.8% CAGR. Explore product types, organic demand, distribution channels and regional trends.