


Whey Protein Market
Whey Protein Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Whey Protein Market Size and Trend Analysis
What Is the Growth Outlook for Whey Protein to 2033?
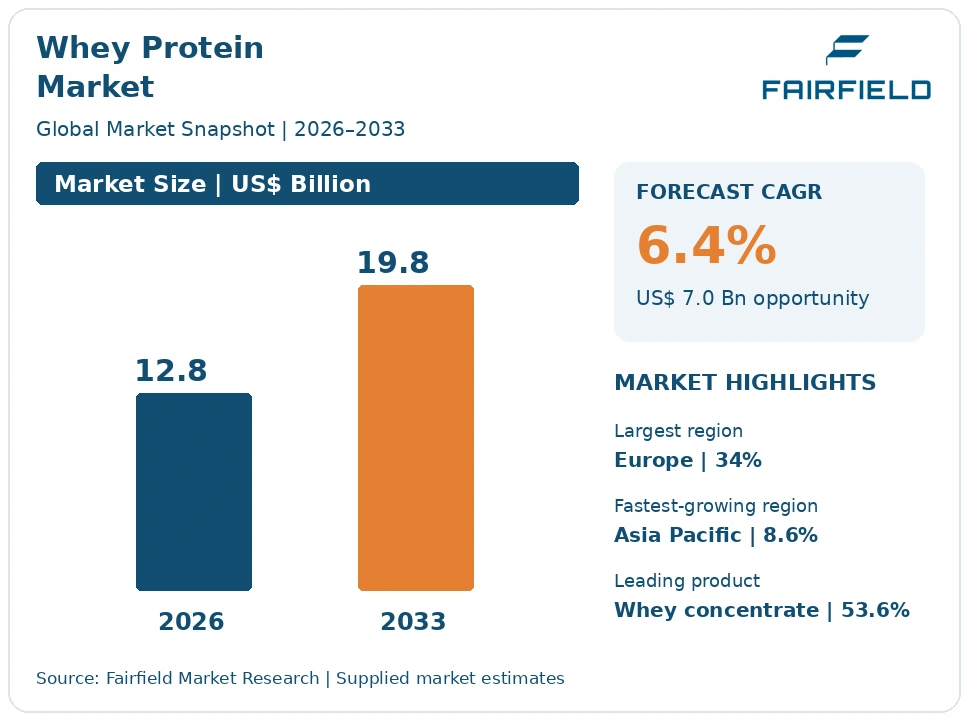
The global Whey Protein market size is expected to be valued at US$ 12.8 billion in 2026 and projected to reach US$ 19.8 billion by 2033, growing at a CAGR of 6.4% between 2026 and 2033.
The industry grew at a historical CAGR near 5.2% between 2020 and 2025, with volume steady and value driven by the shift from commodity concentrate toward higher-purity fractions. Three factors shape the forecast. Protein positioning has moved out of sports nutrition into everyday foods and drinks, widening the formulator base. Clinical nutrition and specialised infant formula continue to absorb hydrolysates and demineralised fractions at premium prices. Filtration capacity investment is converting more of the cheese stream into protein rather than feed-grade powder. Growth is therefore value-led rather than volume-led, and the pace is set as much by cheese output as by protein demand.
Key Report Takeaways
- By Product Type: Whey protein concentrate held 53.6% share in 2026, while whey protein isolate is projected to expand at a 7.9% CAGR through 2033, as formulators seek higher protein density with minimal lactose and fat.
- By Form: Powder held 89.4% share in 2026, while liquid whey protein is projected to grow at a 7.4% CAGR through 2033, supported by regional beverage plants that buy concentrated liquid streams and avoid drying costs.
- By Application: Sports and active nutrition held 34.8% share in 2026, while clinical and medical nutrition is projected to advance at an 8.2% CAGR through 2033, on hospital and home-care formulation demand.
- By Distribution Channel: Direct sales to manufacturers held 64.0% share in 2026, while online business-to-business platforms are projected to rise at an 8.4% CAGR through 2033, as smaller brands source smaller lots.
- By Geography: Europe held 34.0% share in 2026, while Asia Pacific is projected to grow at an 8.6% CAGR through 2033, on rising dairy protein use in beverages and infant nutrition.
Global Whey Protein Market Trends and Insights
Drivers Impact Analysis
Two forces account for most of the forecast growth in dairy protein ingredient sales.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Protein fortification of mainstream foods and beverages | High | Global, led by North America and Europe | Medium term (2–4 years) |
| Expanding cheese output enlarging the available whey stream | Medium | Europe, North America, Asia Pacific | Long term (≥4 years) |
Protein Fortification of Everyday Foods Widens the Whey Protein Customer Base
Protein has become a mainstream label feature rather than a sports nutrition specialism, and that shift expands the number of companies buying whey fractions. Bakery, confectionery, ready meals, yoghurt, soups and bottled drinks now carry protein content statements, and each reformulation creates recurring ingredient demand from manufacturers that previously bought none.
The regulatory basis matters here. Under the EU Nutrition and Health Claims Regulation and Commission Regulation (EU) No 432/2012, protein carries authorised claims for the growth and maintenance of muscle mass and the maintenance of normal bones, so a compliant label can be built around protein content. Whey fits because it dissolves well, tolerates processing and carries a neutral flavour at the isolate end of the range. Formulators also value its functional behaviour in foaming, gelling and emulsification, which lets protein content rise without separate texturising ingredients.
Rising Global Cheese Production Enlarges the Whey Stream Available for Protein Recovery
Cheese output growth is the quiet driver behind whey protein volumes, because every tonne of cheese releases roughly nine tonnes of liquid whey. As cheese consumption rises across Europe, North America and increasingly Asia Pacific, processors have more raw stream to work with, and the economics of recovering protein from it improve with scale.
The mechanism runs through capital allocation. Liquid whey spoils quickly and is costly to transport, so value depends on processing near the cheese plant. Membrane filtration and ion-exchange installations let a plant move from feed-grade powder into concentrate, isolate and demineralised fractions worth several times more per tonne. Dairy co-operatives and private processors have steadily added this capacity, supported by hygiene and approval requirements under Regulation (EC) No 853/2004 in Europe and comparable US FDA dairy standards.
Restraints Impact Analysis
Two structural constraints limit how fast supply can respond to protein demand.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Whey supply tied to the cheese production cycle | High | Global | Long term (≥4 years) |
| Plant protein substitution and dairy-free positioning | Medium | North America, Europe, Asia Pacific | Medium term (2–4 years) |
Whey Supply Is Set by the Cheese Cycle, Not by Protein Demand, Which Drives Price Volatility
Whey is a co-product of cheesemaking, and this single fact governs the market. No processor makes whey on purpose; the volume available depends on how much cheese is produced, which in turn depends on milk supply, cheese demand and farmgate economics. When protein demand runs ahead of the cheese cycle, buyers cannot order more raw material into existence, and high-protein isolate moves into shortage with sharp price increases.
The cause is physical rather than commercial. Each tonne of cheese yields a fixed quantity of whey solids, and only part of that is protein, so isolate output is capped by the stream a plant receives. Capacity added during a tight period arrives years later, often as the cycle turns. Buyers manage the exposure through annual contracts, dual sourcing and reformulation clauses, but the volatility is embedded in the supply structure itself.
Plant Protein Substitution and Dairy-Free Positioning Cap Whey Protein Volume Growth
Plant proteins take share wherever price, label positioning or dietary preference outweighs functional performance. Pea, soy, rice and blended plant systems are specified in bars, beverages and meal replacements aimed at consumers avoiding dairy, and retailers allocate shelf space to those claims. Lactose intolerance positioning works against concentrate in particular, since it carries more lactose than isolate.
The competitive pressure is widening. Price is part of it, as plant isolates are often cheaper per unit of protein and are not exposed to the cheese cycle. Flavour and texture gaps that once protected dairy protein have narrowed with improved processing. Over a longer horizon, precision-fermented dairy proteins produced without animals present a more direct challenge, because they target the same functional and label territory as whey rather than offering an alternative to it.
Market Opportunities
Clinical Nutrition and Specialised Infant Formula Open the Highest-Value Whey Protein Revenue Pool
Clinical nutrition and specialised infant formula are the richest revenue pools in dairy protein, because both buy purified fractions at prices far above commodity concentrate. Hydrolysed whey, whey protein isolate and demineralised whey command premiums that justify ion-exchange and electrodialysis investment, and contract volumes are more stable than retail-driven demand.
Dairy processors with pharmaceutical-grade quality systems are positioned to capture this, since hospital and formula customers audit plants closely. Demand comes from ageing populations in Europe, Japan and North America, where oral nutritional products are supplied through hospitals, care settings and pharmacies. Specialised infant formula adds a second pool: Commission Delegated Regulation (EU) 2016/127 sets detailed compositional and labelling requirements for infant and follow-on formula in Europe, including provisions for formula manufactured from protein hydrolysates, which favours suppliers able to document consistent hydrolysate quality.
Clear Acidic Ready-to-Drink Beverages Create a New Whey Protein Isolate Application
Clear, shelf-stable protein beverages represent a genuinely new application rather than a larger version of an old one. These drinks sit at low pH, where most proteins cloud or precipitate, and only highly purified whey protein isolate stays soluble through heat treatment. That requirement locks in a premium grade and excludes concentrate entirely.
Beverage companies and contract fillers create the demand, and convenience retail distributes it, which brings dairy protein to buyers who would not purchase a tub of powder. Suppliers capture the pool by selling application support alongside the ingredient: pH and mineral specifications, heat-stability data, flavour masking guidance and pilot-plant trials conducted on the customer’s own filling equipment. The category also travels well into warmer markets where powdered formats sell poorly, giving processors in Europe and Oceania an export route into Asia Pacific beverage manufacturing.
Segment Analysis
By Product Type: Concentrate Holds Volume While Isolate Captures Value Growth
Whey protein concentrate held 53.6% of market value in 2026, spanning grades from low-protein powders used in bakery and confectionery to higher-protein concentrates used in sports nutrition. It leads on cost per unit of protein and on availability, since it requires less processing than purified fractions and is produced at most cheese-adjacent plants.
Whey protein isolate is the fastest-growing product type at a 7.9% CAGR through 2033. Formulators choose it for high protein density with minimal lactose and fat, which suits clear beverages, lactose-sensitive positioning and clinical products. Hydrolysed whey serves specialised infant formula and medical nutrition, while demineralised and native whey supply infant nutrition and premium applications. The shift toward purified fractions raises revenue per tonne of milk solids, which is how processors offset flat raw-material availability.
By Form: Powder Dominates Trade While Liquid Whey Grows Around Local Plants
Powder accounted for 89.4% of the market in 2026. Drying makes the protein shelf-stable and shippable, which is essential in a trade where production sits beside cheese plants and consumption is global. Powder also suits the dry-blending operations that dominate sports nutrition and bakery manufacturing.
Liquid whey protein is growing faster, at a 7.4% CAGR to 2033. Beverage and dairy manufacturers located near a processing site can take concentrated liquid streams directly, avoiding the energy cost of drying and rehydration and preserving protein functionality. Cold-chain requirements and short shelf life confine this to regional supply relationships. The practical effect is a two-tier market: powder for export and broad distribution, liquid for integrated local chains where the freight distance is short enough to make it work.
By Application: Sports Nutrition Leads as Clinical and Medical Nutrition Accelerates
Sports and active nutrition held 34.8% share in 2026, the largest application block. Powders, bars and ready-to-drink products built on whey remain the default in this category, supported by broad retail distribution and consumer familiarity with the ingredient.
Clinical and medical nutrition is the fastest-growing application at an 8.2% CAGR through 2033, as hospital, care-home and home-delivered nutrition products are formulated with purified dairy protein fractions and bought on long-term tenders. Infant formula contributes high-value demand for demineralised and hydrolysed grades. Bakery and confectionery use lower-protein concentrates for texture and browning as much as for protein content. Beverages add the clear acidic format, and animal feed absorbs lower-value streams. This spread insulates processors from any single consumer trend.
By Distribution Channel: Direct Supply Leads While Online Business-to-Business Trade Expands
Direct sales to manufacturers accounted for 64.0% of ingredient value in 2026. Large food, beverage, formula and nutrition companies contract directly with processors, because they need specification control, audit access, volume security and agreed pricing mechanisms across a full year.
Online business-to-business platforms form the fastest-growing channel at an 8.4% CAGR to 2033. Smaller brands and contract manufacturers buy in smaller lots, compare specifications and documentation digitally, and value shorter lead times over contract pricing. Ingredient distributors and traders hold the middle ground, breaking bulk, carrying inventory through tight periods and serving markets where a processor has no local presence or sales office. Their role grows during shortages, when access to material matters more than the quoted price per tonne. The split means processors must support two very different buying behaviours at once.
Geography Analysis
North America Combines Large-Scale Cheese Output With Deep Sports Nutrition Demand
North America held 28.0% of global whey protein value in 2026, growing at a 5.4% CAGR to 2033. The United States is the core, with very large cheese plants in Wisconsin, California, Idaho and New Mexico generating the whey stream, and with the deepest sports and active nutrition consumer base anywhere. Canada adds processing capacity under a supply-managed milk system.
Regulation shapes product claims and manufacture: US FDA food standards govern dairy processing, while protein powders sold as supplements fall under the dietary supplement framework with its own manufacturing practice requirements. The region is also the largest exporter of high-protein powders. The change worth watching is the steady reallocation of capacity from commodity concentrate toward isolate and specialised fractions, which lifts value without needing more milk.
Which Region Is Leading the Whey Protein Market?
Europe leads the whey protein market with a 34.0% share in 2026 and a 5.5% CAGR to 2033, because it combines the world’s largest cheese industry with the most advanced fractionation capacity. Germany, France, the Netherlands, Ireland and Denmark contribute most of the output, with co-operatives processing whey alongside cheese at the same sites.
Rules underpin the position. Regulation (EC) No 853/2004 sets the hygiene requirements that govern dairy establishments, Commission Regulation (EU) No 432/2012 defines the authorised protein claims used on labels, and Commission Delegated Regulation (EU) 2016/127 governs infant and follow-on formula composition. That framework supports exports into markets that accept EU certification. Milk supply constraints and environmental compliance costs limit volume growth, pushing processors further toward high-purity fractions.
Which Region Is Growing Fastest in the Whey Protein Market?
Asia Pacific is growing fastest in the whey protein market, at an 8.6% CAGR between 2026 and 2033, from a 26.0% share in 2026. China leads on infant formula and sports nutrition demand, Japan and Korea on clinical nutrition and functional beverages, and India on a rapidly expanding active nutrition consumer base. Australia and New Zealand supply the region as exporters with their own cheese-derived streams.
Most markets here are net importers of protein fractions, because domestic cheese production is small relative to protein demand. That dependence exposes buyers to global price swings and to import documentation requirements. The opportunity sits in beverage formats and in locally manufactured nutrition brands, which are moving from imported finished goods to imported ingredients processed at home.
Latin America Builds Whey Protein Demand on Dairy Processing and Retail Nutrition Growth
Latin America accounted for 7.0% of the market in 2026, growing at a 6.6% CAGR through 2033. Brazil, Mexico and Argentina drive demand, with Brazil holding the largest active nutrition retail base and Argentina operating an export-oriented dairy sector that produces whey powders of its own.
Barriers are significant. Currency volatility raises the landed cost of imported isolate, local fractionation capacity is limited to a few plants, and distribution outside major cities is fragmented. Price sensitivity keeps concentrate dominant and slows the move to purified grades. The change underway is domestic investment in membrane filtration at existing cheese plants, which would reduce import dependence and give regional brands a more stable supply than the import market provides.
Middle East & Africa Depends on Imports While Local Nutrition Manufacturing Expands
Middle East & Africa held 5.0% of the market in 2026 and is projected to grow at a 7.2% CAGR through 2033 from a small base. The Gulf states, Saudi Arabia and the United Arab Emirates in particular, drive demand through nutrition manufacturing, hospital procurement and a young consumer population. South Africa, Egypt and Morocco add food and beverage formulation demand.
The region produces little cheese relative to its protein consumption, so almost all material is imported, mostly from Europe and Oceania. Barriers include freight costs, heat exposure during transit, halal certification requirements and limited cold-chain depth. The opportunity lies in local blending and filling operations, which are being built to serve regional demand and reduce reliance on imported finished nutrition products.
Competitive Landscape
The whey protein market is moderately concentrated, with a clear split between dairy co-operatives that control raw milk and specialist ingredient businesses that control purification technology. Large processors such as Lactalis Ingredients, Arla Foods Ingredients Group P/S, Fonterra Co-operative Group Limited, Glanbia plc and FrieslandCampina Ingredients hold a substantial share of traded high-protein material, while regional cheese makers supply commodity concentrate into a fragmented middle market. Vertical position matters more than brand: a company that owns both the cheese plant and the filtration line captures the margin between feed-grade powder and isolate.
Competition rests on raw material access, purification capability and documentation. Buyers in infant formula and clinical nutrition audit plants in detail and require consistent amino acid profiles, low microbial counts and reliable allergen controls, which narrows the supplier list sharply at the top end. In commodity concentrate, the basis of competition reverts to price and availability, and traders move material between regions when price gaps open. Leprino Foods Company, Hilmar Cheese Company, Agropur Cooperative and Saputo Inc. illustrate the cheese-led route into protein, while Carbery Group, Kerry Group plc, Valio Ltd and Milk Specialties Global show the specialist and application-support route.
Strategic behaviour concentrates on moving up the value ladder. Processors invest in membrane filtration, ion exchange and electrodialysis to convert more of the stream into isolate, demineralised whey and hydrolysates, and they add application laboratories so formulators can test beverage and clinical systems before committing. Several groups have also built positions in infant nutrition ingredients, where approval barriers are highest and contracts are longest. The common direction is to reduce exposure to commodity pricing by selling specification and service rather than tonnes.
Whey Protein Industry Leaders
- Glanbia plc
- Arla Foods Ingredients Group P/S
- Fonterra Co-operative Group Limited
- Lactalis Ingredients
- Leprino Foods Company
Recent Industry Developments
May 2012: Commission Regulation (EU) No 432/2012 established the EU list of permitted health claims, including the authorised protein claims for the growth and maintenance of muscle mass and the maintenance of normal bones – this remains the legal basis for protein label positioning across Europe.
February 2020: Commission Delegated Regulation (EU) 2016/127 became applicable for infant formula and follow-on formula, setting compositional and labelling requirements including provisions for formula manufactured from protein hydrolysates – it raised documentation demands on suppliers of hydrolysed and demineralised fractions.
December 2024: The US FDA issued a final rule updating the definition of the “healthy” nutrient content claim for food labelling – it changes which fortified and protein-containing formulations can carry the claim and prompts reformulation reviews.
January 2025: The US FDA proposed a front-of-package nutrition information box for most packaged foods – front-of-pack presentation would increase the visibility of nutrient content, affecting how protein-fortified products are formulated and positioned.
Whey Protein Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 12.8 Billion |
| Market Size 2033 | US$ 19.8 Billion |
| CAGR 2026–2033 | 6.4% |
| Absolute Dollar Opportunity | US$ 7.0 Billion |
| Largest Market | Europe (34.0% share in 2026) |
| Fastest-Growing Market | Asia Pacific (8.6% CAGR) |
| Market Concentration | Medium |
| Major Players | Glanbia plc, Arla Foods Ingredients Group P/S, Fonterra Co-operative Group Limited, Lactalis Ingredients |
This study sizes global whey protein ingredient sales, covering whey protein concentrate at all protein levels, whey protein isolate, hydrolysed whey protein and demineralised and native whey sold to manufacturers. Finished consumer products such as retail powders, bars and ready-to-drink shakes are excluded, since including them would raise the figure considerably. The base year is 2025, with forecasts for 2026–2033 stated in US$ Billion.
Whey Protein Market Segmentation
Product Type
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
Form
- Powder
- Liquid
Application
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
Distribution Channel
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Whey Protein Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Protein Fortification of Everyday Foods Widens the Whey Protein Customer Base
- Rising Global Cheese Production Enlarges the Whey Stream Available for Protein Recovery
- Restraints
- Whey Supply Is Set by the Cheese Cycle, Not by Protein Demand, Which Drives Price Volatility
- Plant Protein Substitution and Dairy-Free Positioning Cap Whey Protein Volume Growth
- Market Opportunities
- Clinical Nutrition and Specialised Infant Formula Open the Highest-Value Whey Protein Revenue Pool
- Clear Acidic Ready-to-Drink Beverages Create a New Whey Protein Isolate Application
- Drivers
- Global Whey Protein Market Outlook, 2020–2033
- Global Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
- Global Whey Protein Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Powder
- Liquid
- Global Whey Protein Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
- Global Whey Protein Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
- Global Whey Protein Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Whey Protein Market Outlook, 2020–2033
- North America Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
- North America Whey Protein Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Powder
- Liquid
- North America Whey Protein Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
- North America Whey Protein Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
- North America Whey Protein Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Whey Protein Market Outlook, by Product Type, 2020–2033
- United States Whey Protein Market Outlook, by Form, 2020–2033
- United States Whey Protein Market Outlook, by Application, 2020–2033
- United States Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Canada Whey Protein Market Outlook, by Product Type, 2020–2033
- Canada Whey Protein Market Outlook, by Form, 2020–2033
- Canada Whey Protein Market Outlook, by Application, 2020–2033
- Canada Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- North America Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Whey Protein Market Outlook, 2020–2033
- Europe Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
- Europe Whey Protein Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Powder
- Liquid
- Europe Whey Protein Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
- Europe Whey Protein Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
- Europe Whey Protein Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Whey Protein Market Outlook, by Product Type, 2020–2033
- Germany Whey Protein Market Outlook, by Form, 2020–2033
- Germany Whey Protein Market Outlook, by Application, 2020–2033
- Germany Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- France Whey Protein Market Outlook, by Product Type, 2020–2033
- France Whey Protein Market Outlook, by Form, 2020–2033
- France Whey Protein Market Outlook, by Application, 2020–2033
- France Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Netherlands Whey Protein Market Outlook, by Product Type, 2020–2033
- Netherlands Whey Protein Market Outlook, by Form, 2020–2033
- Netherlands Whey Protein Market Outlook, by Application, 2020–2033
- Netherlands Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Ireland Whey Protein Market Outlook, by Product Type, 2020–2033
- Ireland Whey Protein Market Outlook, by Form, 2020–2033
- Ireland Whey Protein Market Outlook, by Application, 2020–2033
- Ireland Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Denmark Whey Protein Market Outlook, by Product Type, 2020–2033
- Denmark Whey Protein Market Outlook, by Form, 2020–2033
- Denmark Whey Protein Market Outlook, by Application, 2020–2033
- Denmark Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Europe Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Whey Protein Market Outlook, 2020–2033
- Asia Pacific Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
- Asia Pacific Whey Protein Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Powder
- Liquid
- Asia Pacific Whey Protein Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
- Asia Pacific Whey Protein Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
- Asia Pacific Whey Protein Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Whey Protein Market Outlook, by Product Type, 2020–2033
- China Whey Protein Market Outlook, by Form, 2020–2033
- China Whey Protein Market Outlook, by Application, 2020–2033
- China Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Japan Whey Protein Market Outlook, by Product Type, 2020–2033
- Japan Whey Protein Market Outlook, by Form, 2020–2033
- Japan Whey Protein Market Outlook, by Application, 2020–2033
- Japan Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Korea Whey Protein Market Outlook, by Product Type, 2020–2033
- Korea Whey Protein Market Outlook, by Form, 2020–2033
- Korea Whey Protein Market Outlook, by Application, 2020–2033
- Korea Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- India Whey Protein Market Outlook, by Product Type, 2020–2033
- India Whey Protein Market Outlook, by Form, 2020–2033
- India Whey Protein Market Outlook, by Application, 2020–2033
- India Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Australia Whey Protein Market Outlook, by Product Type, 2020–2033
- Australia Whey Protein Market Outlook, by Form, 2020–2033
- Australia Whey Protein Market Outlook, by Application, 2020–2033
- Australia Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- New Zealand Whey Protein Market Outlook, by Product Type, 2020–2033
- New Zealand Whey Protein Market Outlook, by Form, 2020–2033
- New Zealand Whey Protein Market Outlook, by Application, 2020–2033
- New Zealand Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Asia Pacific Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Whey Protein Market Outlook, 2020–2033
- Latin America Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
- Latin America Whey Protein Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Powder
- Liquid
- Latin America Whey Protein Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
- Latin America Whey Protein Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
- Latin America Whey Protein Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Whey Protein Market Outlook, by Product Type, 2020–2033
- Brazil Whey Protein Market Outlook, by Form, 2020–2033
- Brazil Whey Protein Market Outlook, by Application, 2020–2033
- Brazil Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Mexico Whey Protein Market Outlook, by Product Type, 2020–2033
- Mexico Whey Protein Market Outlook, by Form, 2020–2033
- Mexico Whey Protein Market Outlook, by Application, 2020–2033
- Mexico Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Argentina Whey Protein Market Outlook, by Product Type, 2020–2033
- Argentina Whey Protein Market Outlook, by Form, 2020–2033
- Argentina Whey Protein Market Outlook, by Application, 2020–2033
- Argentina Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Latin America Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Whey Protein Market Outlook, 2020–2033
- Middle East & Africa Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
- Middle East & Africa Whey Protein Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Powder
- Liquid
- Middle East & Africa Whey Protein Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
- Middle East & Africa Whey Protein Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
- Middle East & Africa Whey Protein Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Whey Protein Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Whey Protein Market Outlook, by Form, 2020–2033
- Saudi Arabia Whey Protein Market Outlook, by Application, 2020–2033
- Saudi Arabia Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- United Arab Emirates Whey Protein Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Whey Protein Market Outlook, by Form, 2020–2033
- United Arab Emirates Whey Protein Market Outlook, by Application, 2020–2033
- United Arab Emirates Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- South Africa Whey Protein Market Outlook, by Product Type, 2020–2033
- South Africa Whey Protein Market Outlook, by Form, 2020–2033
- South Africa Whey Protein Market Outlook, by Application, 2020–2033
- South Africa Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Egypt Whey Protein Market Outlook, by Product Type, 2020–2033
- Egypt Whey Protein Market Outlook, by Form, 2020–2033
- Egypt Whey Protein Market Outlook, by Application, 2020–2033
- Egypt Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Morocco Whey Protein Market Outlook, by Product Type, 2020–2033
- Morocco Whey Protein Market Outlook, by Form, 2020–2033
- Morocco Whey Protein Market Outlook, by Application, 2020–2033
- Morocco Whey Protein Market Outlook, by Distribution Channel, 2020–2033
- Middle East & Africa Whey Protein Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Lactalis Ingredients
- Arla Foods Ingredients Group P/S
- Glanbia plc
- FrieslandCampina Ingredients
- Fonterra Co-operative Group Limited
- Saputo Inc.
- Agropur Cooperative
- Leprino Foods Company
- Hilmar Cheese Company
- Carbery Group
- Kerry Group plc
- Valio Ltd
- Milk Specialties Global
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Whey Protein Concentrate
- Whey Protein Isolate
- Hydrolysed Whey Protein
- Demineralised and Native Whey
Form
- Powder
- Liquid
Application
- Sports and Active Nutrition
- Clinical and Medical Nutrition
- Infant Formula
- Bakery and Confectionery
- Beverages
- Animal Feed
Distribution Channel
- Direct Sales to Manufacturers
- Ingredient Distributors and Traders
- Online Business-to-Business Platforms
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The whey protein ingredient market is valued at US$ 12.8 billion in 2026, covering concentrate, isolate, hydrolysate and demineralised fractions sold to manufacturers.
Sales are projected to reach US$ 19.8 billion by 2033, a CAGR of 6.4%, an absolute dollar opportunity of US$ 7.0 billion across the forecast period.
Whey protein concentrate leads with 53.6% share in 2026, helped by the lowest cost per unit of protein and the widest production availability.
Whey protein isolate grows fastest among product types at 7.9% CAGR, while Asia Pacific is the fastest-growing region at 8.6% CAGR.
Europe leads with 34.0% share in 2026, combining the largest cheese industry with advanced fractionation capacity and established export certification.
Related Reports
Kombucha Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The Kombucha Market is projected to grow from US$ 3.2 billion in 2026 to US$ 4.8 billion by 2033 at a 6.0% CAGR. Explore trends and leading segments.
Insect Protein Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Insect Protein Market is projected to grow from US$ 1.03 billion in 2026 to US$ 3.17 billion by 2033 at a 17.4% CAGR. Explore trends and key segments.
Functional Mushroom Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the Functional Mushroom Market, projected to grow from US$ 2.6 billion in 2026 to US$ 4.4 billion by 2033 at a 7.8% CAGR. See trends and segments.
Food Preservatives Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The food preservatives market is valued at US$ 3.67 billion in 2026 and projected to reach US$ 4.97 billion by 2033 at a CAGR of 4.4%.
Beeswax Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The beeswax market is valued at US$ 0.7 billion in 2026 and projected to reach US$ 1.0 billion by 2033 at a CAGR of 5.2%.
Adaptogens Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The adaptogens market is valued at US$ 17.09 billion in 2026 and projected to reach US$ 29.08 billion by 2033, growing at a CAGR of 7.9%.