


Gene Switch Market
Gene Switch Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Gene Switch Market Size and Trend Analysis
How Fast Is the Gene Switch Market Growing?
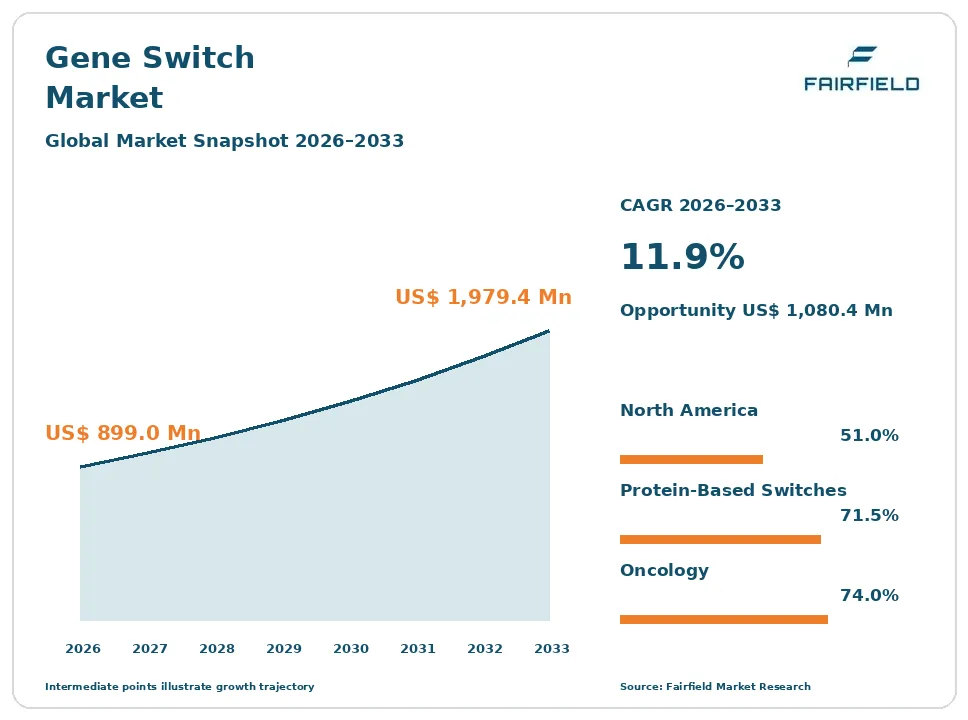
The global gene switch market size is expected to be valued at US$ 899.0 million in 2026 and projected to reach US$ 1,979.4 million by 2033, growing at a CAGR of 11.9% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 10.4%, as more CAR-T and gene therapy developers built control systems into their products. Three factors now drive growth: the need for a safety switch that can shut down engineered cells after serious side effects, the rise of CAR-T cell therapy in cancer and autoimmune disease, and progress in synthetic biology tools that turn genes on and off with a drug. Revenue comes mainly from licensing deals, upfront payments, and milestone fees paid by therapy developers. The market is moving toward small-molecule control using approved drugs, RNA-based switches that avoid immune reactions, and switches for in vivo gene therapy. Large pharma partnerships and new academic tools in 2025 show strong interest in safer, more controllable cell and gene therapies.
Key Report Takeaways
- By Type of Switch: Protein-Based Switches held 71.5% share in 2026, while RNA-Based Switches are projected to expand at a 15.2% CAGR through 2033, driven by lower immune risk and easier design for in vivo therapies.
- By Application: Management of Treatment-Related Toxicity held 58.0% share in 2026, while Regulation of Gene Expression is projected to expand at a 13.8% CAGR through 2033, driven by dose-tunable gene therapies.
- By Therapeutic Area: Oncology held 74.0% share in 2026, while Immunological Disorders are projected to expand at a 16.1% CAGR through 2033, driven by CAR-T programs for lupus and other autoimmune diseases.
- By Region: North America held 51.0% share in 2026, while Asia Pacific is projected to expand at a 14.6% CAGR through 2033, driven by fast growth in cell therapy trials in China and Japan.
Global Gene Switch Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Need for safety switches in cell therapy | High | North America, Europe, Asia Pacific | Medium term (2-4 years) |
| Growth of CAR-T and gene therapy pipelines | High | Global | Long term (≥4 years) |
Two drivers carry the strongest influence on gene switch demand during the forecast period.
Safety Needs Are Driving the Gene Switch Market
The need for a safety switch in cell therapy is the strongest driver of the gene switch market. Developers want a way to stop engineered cells if patients suffer serious side effects.
The mechanism is simple: a switch built into the cell lets doctors trigger cell death or shut down activity with a drug. CAR-T therapies can cause cytokine release syndrome and nerve damage, and in rare cases T-cell cancers, which led the U.S. Food and Drug Administration to add boxed warnings in 2024. Switches such as the inducible caspase-9 system, activated by rimiducid, give doctors a way to respond quickly. MD Anderson Cancer Center and Phoenix SENOLYTIX signed a cross-licensing deal in 2025 to improve this technology. Regulators and investors increasingly favor therapies with built-in controls. These factors push more developers to license switch technology.
Pipeline Growth Is Expanding the Gene Switch Market
The growth of CAR-T cell therapy and gene therapy pipelines is expanding the gene switch market. More programs mean more licensing deals for switch platforms.
The cause is a strong flow of new therapies into clinical trials. Thousands of cell and gene therapy trials are underway worldwide, with new targets in solid tumors and autoimmune disease. Solid tumor CAR-T programs carry higher safety risks, so they benefit most from switches. Allogeneic, or off-the-shelf, cell therapies made by Cellectis, Sana Biotechnology, and others often include control features. Autolus Therapeutics licensed its safety switch to Cabaletta Bio for autoimmune programs. Gene therapies for chronic diseases need adjustable expression to avoid overdosing. These factors widen demand for switches across therapeutic areas.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Immunogenicity and technical complexity | High | Global | Medium term (2-4 years) |
| Regulatory uncertainty and high development costs | Medium | North America, Europe | Long term (≥4 years) |
Two restraints limit how quickly the gene switch market grows.
Technical Complexity Slows the Gene Switch Market
Immunogenicity and technical complexity slow the gene switch market. Many switches are hard to design and can trigger immune reactions.
The specific causes lie in biology. Protein-based switches often use parts taken from bacteria or viruses, which the immune system may attack, removing the engineered cells too early. Some switches leak, meaning genes stay partly on when they should be off. Others respond slowly or need drugs with side effects of their own. Adding a switch also takes up space in viral vectors, which have limited capacity. Testing a switch adds time and cost to development. These issues make some developers skip switches entirely and rely on other safety measures, such as careful dosing and steroid treatment. Switches that work in mice do not always work in people. These factors slow adoption, especially for smaller biotech companies.
Regulatory Uncertainty Restricts the Gene Switch Market
Regulatory uncertainty and high development costs restrict the gene switch market. Approval pathways for switch-enabled therapies are still evolving.
The underlying causes are the novelty of the technology and the need for extra safety data. Regulators must review both the therapy and the drug used to trigger the switch, which can add trials and paperwork. The activating drug may itself need approval, as with rimiducid. Few switch-enabled therapies have reached the market, so there are limited examples to follow. Funding for cell and gene therapy biotechs fell after 2021, and several companies, including Bellicum Pharmaceuticals, wound down operations. High manufacturing costs for cell therapies also leave less budget for extra features. These factors reduce the number of buyers able to pay for switch licenses and slow deal flow.
Market Opportunities
Autoimmune Cell Therapies Open a High-Growth Revenue Pool
CAR-T therapies for autoimmune disease open a high-growth revenue pool in the gene switch market. Patients with lupus, myasthenia gravis, and multiple sclerosis are now being treated in trials.
Switch developers with proven safety platforms can capture this opportunity. Patients with autoimmune disease are often less sick than cancer patients, so safety expectations are higher. A switch gives doctors more control and may make regulators more comfortable. Autolus Therapeutics and Cabaletta Bio have already worked together in this area. Large drug companies are investing heavily in autoimmune cell therapy. Licensing to these programs could bring upfront and milestone payments for several years. Hospitals treating autoimmune patients outside cancer centers may also prefer therapies with an easy off-switch, which could become a selling point. Switches could also allow lower-cost outpatient treatment.
Small-Molecule Control Creates a Platform Revenue Pool
Small-molecule control of gene expression creates a platform revenue pool in the gene switch market. Switches controlled by approved, safe drugs are easier to use in patients.
Academic groups and startups with new switch designs can capture this opportunity. In 2025, Weill Cornell Medicine researchers unveiled Cyclone, a switch controlled by the antiviral drug acyclovir. The University of Kentucky reported a gene switch that turns a risky Alzheimer’s gene variant into a protective one in mice. Tools for inducible gene expression also support research and drug discovery. Licensing these platforms to drug developers could open new uses in neurology and metabolic disease. Switches controlled by common oral drugs are cheaper and easier for patients than infusions. Companies that turn academic switches into products can capture early licensing revenue.
Segment Analysis
By Type of Switch: Protein-Based Switches Lead While RNA-Based Switches Grow Fastest
Protein-Based Switches held 71.5% share in 2026. These include inducible caspase-9, suicide genes, and receptor-based systems that react to small molecules or antibodies. Most clinical-stage switches belong to this group because they have the longest safety record. Autolus Therapeutics, Precigen, and MD Anderson Cancer Center hold key protein-based platforms.
RNA-Based Switches are the fastest-growing type, expanding at a 15.2% CAGR through 2033. RNA switches use riboswitches or poison exons that respond to drugs, and they add little foreign protein, lowering immune risk. aceRNA Technologies and academic labs lead this work, and synthetic biology advances are improving their precision. For the market, RNA switches widen use in in vivo gene therapy.
By Application: Toxicity Management Leads While Gene Expression Regulation Grows Fastest
Management of Treatment-Related Toxicity held 58.0% share in 2026. A safety switch allows doctors to eliminate CAR-T or other engineered cells if patients develop severe cytokine release syndrome or nerve damage. This is the most common reason developers license switches, especially for CAR-T cell therapy.
Regulation of Gene Expression is the fastest-growing application, expanding at a 13.8% CAGR through 2033. Inducible gene expression lets doctors adjust how much of a therapeutic protein a patient makes, much like changing a drug dose. This suits gene therapies for chronic diseases, such as hormone or enzyme deficiencies, where too much protein can cause harm. Switches also help researchers study gene function in the lab. For the market, this growth opens new licensing opportunities.
By Therapeutic Area: Oncology Leads While Immunological Disorders Grow Fastest
Oncology held 74.0% share in 2026. Most CAR-T and engineered T-cell programs target blood cancers and, increasingly, solid tumors, where safety risks are higher. Cancer programs drive most switch licensing revenue today.
Immunological Disorders are the fastest-growing therapeutic area, expanding at a 16.1% CAGR through 2033. CAR-T trials for lupus, myasthenia gravis, and systemic sclerosis have shown strong early results. Patients with these conditions need a higher safety margin, which favors built-in switches. Large drug companies are buying autoimmune CAR-T developers and investing in new programs. Infectious disease and neurological programs are smaller but growing, supported by new in vivo gene therapy research. For the market, autoimmune programs add a large new customer base.
Geography Analysis
Which Region Is Leading the Gene Switch Market?
North America is leading the gene switch market with a 51.0% share in 2026. The United States hosts most CAR-T developers, switch platform owners, and venture funding for cell and gene therapy. Precigen, Sangamo Therapeutics, Sana Biotechnology, and MD Anderson Cancer Center are based here. The U.S. Food and Drug Administration has approved several CAR-T therapies, creating a strong market for safety features. Canada adds academic research. Key barriers include high development costs. The National Institutes of Health funds much of the basic research behind new switch designs. One change shaping the region is the use of switches in autoimmune CAR-T trials.
Europe Builds the Gene Switch Market Through Cell Therapy Developers
Europe is a major gene switch market. The United Kingdom is home to Autolus Therapeutics, whose RQR8 safety switch has been licensed to other developers, and France hosts Cellectis. Germany, Spain, and the Netherlands run academic CAR-T programs that test switch designs. The European Medicines Agency has approved several CAR-T products, and Italy runs public cell therapy manufacturing programs. Key barriers include fragmented funding and slower reimbursement. Academic centers in Spain produce their own CAR-T therapies for local patients at lower cost. One opportunity is hospital-made CAR-T therapies that include switches.
Which Region Is Growing Fastest in the Gene Switch Market?
Asia Pacific is growing fastest in the gene switch market at a 14.6% CAGR through 2033. China runs more CAR-T clinical trials than any other country and is building its own switch technologies. Japan supports regenerative medicine through fast-track approval rules, and South Korea and Australia have growing cell therapy sectors. Singapore hosts synthetic biology research hubs, and India has approved its first locally made CAR-T therapy. Lower trial costs and faster patient enrollment attract global developers. Chinese biotechs are licensing CAR-T programs to Western companies. Key barriers include intellectual property concerns. One change shaping the region is local licensing deals.
Latin America Develops the Gene Switch Market Through Clinical Research
Latin America is a small but developing gene switch market. Brazil has started producing CAR-T therapies in public research centers, and Argentina and Mexico host clinical trials. Lower costs make the region attractive for some studies. Colombia and Chile are building regulatory frameworks for advanced therapies. Academic groups in Brazil are testing lower-cost manufacturing methods, and public health systems want safer therapies that reduce intensive care use. Global developers sometimes run early studies in the region. Key barriers include limited funding and specialized hospitals. One opportunity is local CAR-T production with built-in safety switches to reduce treatment risks and costs.
Middle East & Africa Adopts the Gene Switch Market Through Research Investment
Middle East & Africa is an early-stage gene switch market. Saudi Arabia, the United Arab Emirates, and Israel are investing in cell and gene therapy centers and clinical trials. Israel has strong academic research in synthetic biology. South Africa runs limited research programs, and Qatar funds genomic studies through national research programs. Patients often travel abroad for cell therapy, which drives local investment. Egypt is also expanding research capacity. Governments in Saudi Arabia and the United Arab Emirates fund genomic medicine. Key barriers include few trained specialists and limited manufacturing. One opportunity is partnerships with global developers to bring switch-enabled therapies.
Competitive Landscape
The gene switch market is moderately concentrated. Autolus Therapeutics, Precigen, Sangamo Therapeutics, Cellectis, Sana Biotechnology, Kiromic BioPharma, aceRNA Technologies, and panCELLa hold key switch platforms, while MD Anderson Cancer Center owns the switch technologies it acquired from Bellicum Pharmaceuticals. Research tool suppliers such as Takara Bio and Thermo Fisher Scientific sell inducible expression systems for laboratories. Close to 50 companies are active in the space.
Companies compete on safety record, speed of switch activation, immune risk, ease of integration into vectors, and the strength of their patents. Most revenue comes from licensing deals with upfront payments, milestones, and royalties rather than product sales. Clinical data showing that a switch works in patients is the strongest selling point, which favors companies with established platforms. Smaller players focus on new designs, such as RNA switches and drug-controlled systems, and often partner with larger therapy developers to fund clinical testing.
Strategic moves show how competition is changing. In September 2025, MD Anderson Cancer Center and Phoenix SENOLYTIX signed a cross-licensing deal on rimiducid-activated switches. In November 2025, Weill Cornell Medicine unveiled the Cyclone switch, and the University of Kentucky reported an in vivo gene switch for Alzheimer’s risk. These moves show competition shifting toward drug-controlled, in vivo platforms.
Three themes shape vendor strategy. First, companies are licensing switches to autoimmune CAR-T developers. Second, they are moving toward approved drugs as triggers. Third, they are building switches for in vivo gene therapy.
Gene Switch Market Industry Leaders
- Autolus Therapeutics
- Precigen
- Sangamo Therapeutics
- Cellectis
- Sana Biotechnology
Recent Industry Developments
- November 2025: Weill Cornell Medicine researchers unveiled Cyclone, a gene switch controlled by the antiviral drug acyclovir - shows safe small-molecule control using an approved drug.
- November 2025: University of Kentucky scientists reported a gene switch that converts APOE4 to protective APOE2 in adult mice - opens gene switch use in neurology.
- September 2025: MD Anderson Cancer Center and Phoenix SENOLYTIX signed a cross-licensing agreement for rimiducid-activated inducible switches, including CaspaCIDe - advances safety switches for cell and gene therapy.
Companies Covered in the Report
- Autolus Therapeutics
- Precigen
- Sangamo Therapeutics
- Cellectis
- Sana Biotechnology
- Kiromic BioPharma
- aceRNA Technologies
- panCELLa
- Phoenix SENOLYTIX
- MD Anderson Cancer Center
- Takara Bio
- Thermo Fisher Scientific
Gene Switch Market Report Scope
This report covers gene switches used to control engineered cells and gene expression, including protein-based and RNA-based switches, for toxicity management and gene expression regulation in oncology, immunology, infectious disease, and neurology. Revenue includes licensing fees, upfront payments, milestones, and royalties. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Million.
Type of Switch
- Protein-Based Switches
- RNA-Based Switches
Application
- Management of Treatment-Related Toxicity
- Regulation of Gene Expression
- Others
Therapeutic Area
- Oncology
- Immunological Disorders
- Infectious Diseases
- Neurological Disorders
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the gene switch market in 2026?
The gene switch market is valued at US$ 899.0 million in 2026, led by protein-based switches and toxicity management uses.
What is the gene switch market forecast to 2033?
The market is projected to reach US$ 1,979.4 million by 2033, growing at an 11.9% CAGR and adding US$ 1,080.4 million.
Which therapeutic area is growing fastest in the gene switch market?
Immunological disorders are growing fastest at a 16.1% CAGR through 2033, driven by CAR-T trials for lupus and other autoimmune diseases.
Which region is growing fastest in the gene switch market?
Asia Pacific is growing fastest at a 14.6% CAGR through 2033, driven by large CAR-T trial activity in China and Japan.
Which region holds the largest gene switch market share?
North America holds the largest share at 51.0% in 2026, supported by many CAR-T developers and switch platform owners.
1. Executive Summary
1.1. Global Gene Switch Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Safety Needs Are Driving the Gene Switch Market
2.3.1.2. Pipeline Growth Is Expanding the Gene Switch Market
2.3.2. Restraints
2.3.2.1. Technical Complexity Slows the Gene Switch Market
2.3.2.2. Regulatory Uncertainty Restricts the Gene Switch Market
2.3.3. Market Opportunities
2.3.3.1. Autoimmune Cell Therapies Open a High-Growth Revenue Pool
2.3.3.2. Small-Molecule Control Creates a Platform Revenue Pool
3. Global Gene Switch Market Outlook, 2020-2033
3.1. Global Gene Switch Market Outlook, by Type of Switch, Value (US$ Million), 2020-2033
3.1.1. Protein-Based Switches
3.1.2. RNA-Based Switches
3.2. Global Gene Switch Market Outlook, by Application, Value (US$ Million), 2020-2033
3.2.1. Management of Treatment-Related Toxicity
3.2.2. Regulation of Gene Expression
3.2.3. Others
3.3. Global Gene Switch Market Outlook, by Therapeutic Area, Value (US$ Million), 2020-2033
3.3.1. Oncology
3.3.2. Immunological Disorders
3.3.3. Infectious Diseases
3.3.4. Neurological Disorders
3.4. Global Gene Switch Market Outlook, by Region, Value (US$ Million), 2020-2033
3.4.1. North America
3.4.2. Europe
3.4.3. Asia Pacific
3.4.4. Latin America
3.4.5. Middle East & Africa
4. North America Gene Switch Market Outlook, 2020-2033
4.1. North America Gene Switch Market Outlook, by Type of Switch, Value (US$ Million), 2020-2033
4.1.1. Protein-Based Switches
4.1.2. RNA-Based Switches
4.2. North America Gene Switch Market Outlook, by Application, Value (US$ Million), 2020-2033
4.2.1. Management of Treatment-Related Toxicity
4.2.2. Regulation of Gene Expression
4.2.3. Others
4.3. North America Gene Switch Market Outlook, by Therapeutic Area, Value (US$ Million), 2020-2033
4.3.1. Oncology
4.3.2. Immunological Disorders
4.3.3. Infectious Diseases
4.3.4. Neurological Disorders
4.4. North America Gene Switch Market Outlook, by Country, Value (US$ Million), 2020-2033
4.4.1. United States Gene Switch Market Outlook, by Type of Switch, 2020-2033
4.4.2. United States Gene Switch Market Outlook, by Application, 2020-2033
4.4.3. United States Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
4.4.4. Canada Gene Switch Market Outlook, by Type of Switch, 2020-2033
4.4.5. Canada Gene Switch Market Outlook, by Application, 2020-2033
4.4.6. Canada Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
5. Europe Gene Switch Market Outlook, 2020-2033
5.1. Europe Gene Switch Market Outlook, by Type of Switch, Value (US$ Million), 2020-2033
5.1.1. Protein-Based Switches
5.1.2. RNA-Based Switches
5.2. Europe Gene Switch Market Outlook, by Application, Value (US$ Million), 2020-2033
5.2.1. Management of Treatment-Related Toxicity
5.2.2. Regulation of Gene Expression
5.2.3. Others
5.3. Europe Gene Switch Market Outlook, by Therapeutic Area, Value (US$ Million), 2020-2033
5.3.1. Oncology
5.3.2. Immunological Disorders
5.3.3. Infectious Diseases
5.3.4. Neurological Disorders
5.4. Europe Gene Switch Market Outlook, by Country, Value (US$ Million), 2020-2033
5.4.1. United Kingdom Gene Switch Market Outlook, by Type of Switch, 2020-2033
5.4.2. United Kingdom Gene Switch Market Outlook, by Application, 2020-2033
5.4.3. United Kingdom Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
5.4.4. France Gene Switch Market Outlook, by Type of Switch, 2020-2033
5.4.5. France Gene Switch Market Outlook, by Application, 2020-2033
5.4.6. France Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
5.4.7. Germany Gene Switch Market Outlook, by Type of Switch, 2020-2033
5.4.8. Germany Gene Switch Market Outlook, by Application, 2020-2033
5.4.9. Germany Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
5.4.10. Spain Gene Switch Market Outlook, by Type of Switch, 2020-2033
5.4.11. Spain Gene Switch Market Outlook, by Application, 2020-2033
5.4.12. Spain Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
5.4.13. Netherlands Gene Switch Market Outlook, by Type of Switch, 2020-2033
5.4.14. Netherlands Gene Switch Market Outlook, by Application, 2020-2033
5.4.15. Netherlands Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
5.4.16. Italy Gene Switch Market Outlook, by Type of Switch, 2020-2033
5.4.17. Italy Gene Switch Market Outlook, by Application, 2020-2033
5.4.18. Italy Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
6. Asia Pacific Gene Switch Market Outlook, 2020-2033
6.1. Asia Pacific Gene Switch Market Outlook, by Type of Switch, Value (US$ Million), 2020-2033
6.1.1. Protein-Based Switches
6.1.2. RNA-Based Switches
6.2. Asia Pacific Gene Switch Market Outlook, by Application, Value (US$ Million), 2020-2033
6.2.1. Management of Treatment-Related Toxicity
6.2.2. Regulation of Gene Expression
6.2.3. Others
6.3. Asia Pacific Gene Switch Market Outlook, by Therapeutic Area, Value (US$ Million), 2020-2033
6.3.1. Oncology
6.3.2. Immunological Disorders
6.3.3. Infectious Diseases
6.3.4. Neurological Disorders
6.4. Asia Pacific Gene Switch Market Outlook, by Country, Value (US$ Million), 2020-2033
6.4.1. China Gene Switch Market Outlook, by Type of Switch, 2020-2033
6.4.2. China Gene Switch Market Outlook, by Application, 2020-2033
6.4.3. China Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
6.4.4. Japan Gene Switch Market Outlook, by Type of Switch, 2020-2033
6.4.5. Japan Gene Switch Market Outlook, by Application, 2020-2033
6.4.6. Japan Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
6.4.7. South Korea Gene Switch Market Outlook, by Type of Switch, 2020-2033
6.4.8. South Korea Gene Switch Market Outlook, by Application, 2020-2033
6.4.9. South Korea Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
6.4.10. Australia Gene Switch Market Outlook, by Type of Switch, 2020-2033
6.4.11. Australia Gene Switch Market Outlook, by Application, 2020-2033
6.4.12. Australia Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
6.4.13. Singapore Gene Switch Market Outlook, by Type of Switch, 2020-2033
6.4.14. Singapore Gene Switch Market Outlook, by Application, 2020-2033
6.4.15. Singapore Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
6.4.16. India Gene Switch Market Outlook, by Type of Switch, 2020-2033
6.4.17. India Gene Switch Market Outlook, by Application, 2020-2033
6.4.18. India Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
7. Latin America Gene Switch Market Outlook, 2020-2033
7.1. Latin America Gene Switch Market Outlook, by Type of Switch, Value (US$ Million), 2020-2033
7.1.1. Protein-Based Switches
7.1.2. RNA-Based Switches
7.2. Latin America Gene Switch Market Outlook, by Application, Value (US$ Million), 2020-2033
7.2.1. Management of Treatment-Related Toxicity
7.2.2. Regulation of Gene Expression
7.2.3. Others
7.3. Latin America Gene Switch Market Outlook, by Therapeutic Area, Value (US$ Million), 2020-2033
7.3.1. Oncology
7.3.2. Immunological Disorders
7.3.3. Infectious Diseases
7.3.4. Neurological Disorders
7.4. Latin America Gene Switch Market Outlook, by Country, Value (US$ Million), 2020-2033
7.4.1. Brazil Gene Switch Market Outlook, by Type of Switch, 2020-2033
7.4.2. Brazil Gene Switch Market Outlook, by Application, 2020-2033
7.4.3. Brazil Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
7.4.4. Argentina Gene Switch Market Outlook, by Type of Switch, 2020-2033
7.4.5. Argentina Gene Switch Market Outlook, by Application, 2020-2033
7.4.6. Argentina Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
7.4.7. Mexico Gene Switch Market Outlook, by Type of Switch, 2020-2033
7.4.8. Mexico Gene Switch Market Outlook, by Application, 2020-2033
7.4.9. Mexico Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
7.4.10. Colombia Gene Switch Market Outlook, by Type of Switch, 2020-2033
7.4.11. Colombia Gene Switch Market Outlook, by Application, 2020-2033
7.4.12. Colombia Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
7.4.13. Chile Gene Switch Market Outlook, by Type of Switch, 2020-2033
7.4.14. Chile Gene Switch Market Outlook, by Application, 2020-2033
7.4.15. Chile Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
8. Middle East & Africa Gene Switch Market Outlook, 2020-2033
8.1. Middle East & Africa Gene Switch Market Outlook, by Type of Switch, Value (US$ Million), 2020-2033
8.1.1. Protein-Based Switches
8.1.2. RNA-Based Switches
8.2. Middle East & Africa Gene Switch Market Outlook, by Application, Value (US$ Million), 2020-2033
8.2.1. Management of Treatment-Related Toxicity
8.2.2. Regulation of Gene Expression
8.2.3. Others
8.3. Middle East & Africa Gene Switch Market Outlook, by Therapeutic Area, Value (US$ Million), 2020-2033
8.3.1. Oncology
8.3.2. Immunological Disorders
8.3.3. Infectious Diseases
8.3.4. Neurological Disorders
8.4. Middle East & Africa Gene Switch Market Outlook, by Country, Value (US$ Million), 2020-2033
8.4.1. Saudi Arabia Gene Switch Market Outlook, by Type of Switch, 2020-2033
8.4.2. Saudi Arabia Gene Switch Market Outlook, by Application, 2020-2033
8.4.3. Saudi Arabia Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
8.4.4. United Arab Emirates Gene Switch Market Outlook, by Type of Switch, 2020-2033
8.4.5. United Arab Emirates Gene Switch Market Outlook, by Application, 2020-2033
8.4.6. United Arab Emirates Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
8.4.7. Israel Gene Switch Market Outlook, by Type of Switch, 2020-2033
8.4.8. Israel Gene Switch Market Outlook, by Application, 2020-2033
8.4.9. Israel Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
8.4.10. South Africa Gene Switch Market Outlook, by Type of Switch, 2020-2033
8.4.11. South Africa Gene Switch Market Outlook, by Application, 2020-2033
8.4.12. South Africa Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
8.4.13. Qatar Gene Switch Market Outlook, by Type of Switch, 2020-2033
8.4.14. Qatar Gene Switch Market Outlook, by Application, 2020-2033
8.4.15. Qatar Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
8.4.16. Egypt Gene Switch Market Outlook, by Type of Switch, 2020-2033
8.4.17. Egypt Gene Switch Market Outlook, by Application, 2020-2033
8.4.18. Egypt Gene Switch Market Outlook, by Therapeutic Area, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. Autolus Therapeutics
9.5.2. Precigen
9.5.3. Sangamo Therapeutics
9.5.4. Cellectis
9.5.5. Sana Biotechnology
9.5.6. Kiromic BioPharma
9.5.7. aceRNA Technologies
9.5.8. panCELLa
9.5.9. Phoenix SENOLYTIX
9.5.10. MD Anderson Cancer Center
9.5.11. Takara Bio
9.5.12. Thermo Fisher Scientific
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Type of Switch | Protein-Based Switches, RNA-Based Switches |
| Application | Management of Treatment-Related Toxicity, Regulation of Gene Expression, Others |
| Therapeutic Area | Oncology, Immunological Disorders, Infectious Diseases, Neurological Disorders |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The gene switch market is valued at US$ 899.0 million in 2026, led by protein-based switches and toxicity management uses.
The market is projected to reach US$ 1,979.4 million by 2033, growing at an 11.9% CAGR and adding US$ 1,080.4 million.
Immunological disorders are growing fastest at a 16.1% CAGR through 2033, driven by CAR-T trials for lupus and other autoimmune diseases.
Asia Pacific is growing fastest at a 14.6% CAGR through 2033, driven by large CAR-T trial activity in China and Japan.
North America holds the largest share at 51.0% in 2026, supported by many CAR-T developers and switch platform owners.
Related Reports
Nanoparticle Formulation Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The nanoparticle formulation market is projected to grow from US$6.80 billion in 2026 to US$12.67 billion by 2033, at a 9.3% CAGR, driven by RNA therapies.
Renal Biomarkers Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The renal biomarkers market is projected to grow from US$1.73 billion in 2026 to US$2.87 billion by 2033, at a 7.5% CAGR, driven by early kidney testing.
Omics-Based Clinical Trials Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Omics-based clinical trials market to grow from US$38.32 Bn in 2026 to US$65.67 Bn by 2033 at 8.0% CAGR. Explore trial phases, indications and regions.
Ocular Hypertension Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Ocular hypertension market to reach US$ 8.05 billion by 2033 at an 8.2% CAGR. Explore drug classes, delivery modes, pharmacy channels and regional trends.
Obesity GLP-1 Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Obesity GLP-1 market to reach US$ 65.20 billion by 2033 at a 13.1% CAGR. Explore drugs, administration routes, pharmacy channels and regional trends.
Upstream Bioprocessing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Upstream bioprocessing market to reach US$ 92.23 billion by 2033 at a 14.3% CAGR. Explore products, use types, manufacturing modes and regional trends.