


Pea Protein Ingredient Market
Pea Protein Ingredient Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Pea Protein Ingredient Market Size and Trend Analysis
How Fast Is the Pea Protein Ingredient Market Growing?
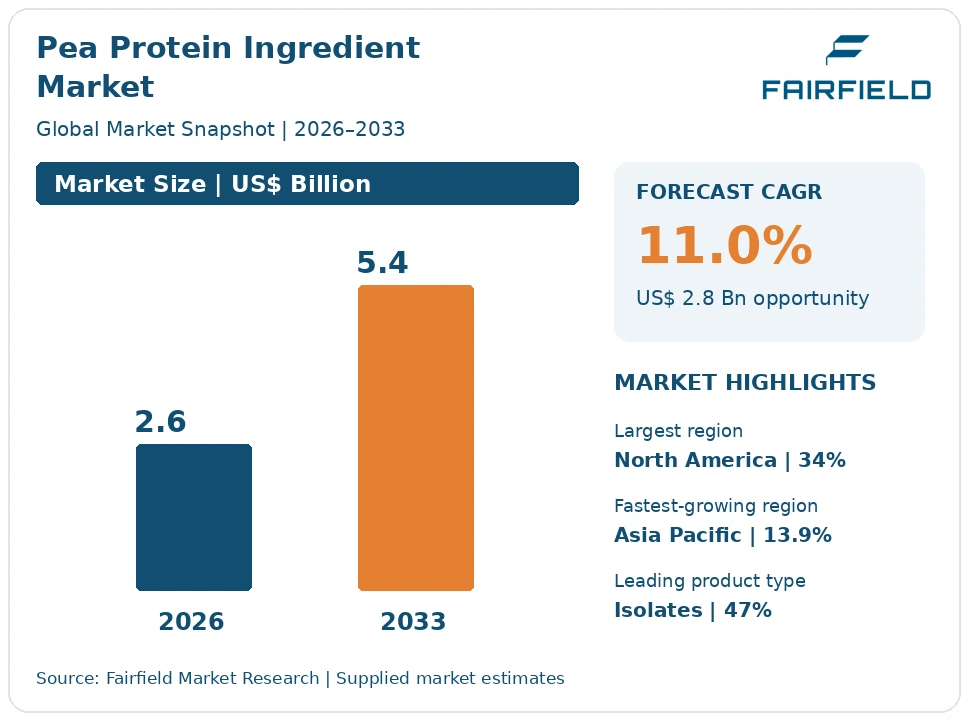
The global Pea Protein Ingredient market size is expected to be valued at US$ 2.6 billion in 2026 and projected to reach US$ 5.4 billion by 2033, growing at a CAGR of 11.0% between 2026 and 2033. These figures cover ingredient sales of pea protein isolate, concentrate, textured pea protein and hydrolysates, and exclude the retail value of finished consumer products made with them.
Between 2020 and 2025 the category expanded at an estimated 14.8% CAGR, a pace set by heavy capacity additions rather than steady offtake. Growth has since normalised. Three factors now carry the market: yellow field pea processing economics that let protein, starch and fibre all earn revenue; the absence of pea from mandatory allergen declaration lists; and steady reformulation of bakery, beverage and sports products. Direction is one of slower but better-quality growth, with utilisation of existing plants improving before new capital arrives.
Key Report Takeaways
- By Product Type: Isolates held 47% share in 2026, while hydrolysates are projected to expand at a 13.4% CAGR through 2033, driven by demand for low-bitterness, rapidly dispersible fractions in ready-to-mix sports formats.
- By Processing Route: Wet fractionation held 79% share in 2026, while dry fractionation is projected to expand at a 13.1% CAGR through 2033, because air-classification plants need far less capital and no effluent treatment.
- By Form: Dry powders held 87% share in 2026, while liquid and dispersion systems are projected to expand at a 12.2% CAGR through 2033, supported by beverage co-packers that prefer pre-hydrated, pre-neutralised protein streams.
- By Application: Meat alternatives held 29% share in 2026, while sports and active nutrition is projected to expand at a 13.6% CAGR through 2033, as blended protein stacks replace single-source powders in everyday formats.
- By Geography: North America held 34% share in 2026, while Asia Pacific is projected to expand at a 13.9% CAGR through 2033, reflecting new pulse processing investment and rising vegetarian protein consumption.
Global Pea Protein Ingredient Market Trends and Insights
Drivers Impact Analysis
Two structural forces explain most of the forecast growth in pea protein ingredients.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Pea starch and fibre co-product offtake improving plant economics | High | North America, Europe | Medium term 2–4 years |
| Allergen-exempt labelling status widening mainstream food use | Medium | Global | Long term ≥4 years |
Pea Starch and Fibre Offtake Is Unlocking Lower-Cost Protein Capacity
Pea protein pricing is decided inside the co-product stack, not by protein demand alone. A wet fractionation plant splits the yellow pea into roughly a quarter protein, half starch and the balance fibre and solubles. When the starch and fibre find paying homes, the protein carries less of the plant’s fixed cost and can be quoted closer to soy. Processors that sell all three streams have been able to hold price while competitors retreat.
The mechanism is demand pull on the non-protein fractions. Pea starch has gained ground in noodles, gluten-free bakery and encapsulation, where its high amylose content sets firm gels. Pea fibre moves into pet food, bakery and meat binding. Pea hull fibre also meets dietary fibre labelling rules in several markets. Each outlet raises plant yield value and lets owners run assets harder, which is what finally lowers delivered protein cost.
Allergen-Exempt Labelling Is Moving Pea Protein Into Mainstream Food Formats
Pea is not listed among the allergens that must be declared under EU or US labelling rules, and that single fact opens shelf space that soy cannot reach. Bakery, cereal, confectionery and school and hospital catering buyers treat a clean allergen declaration as a hard specification. Formulators switching a protein fortificant to pea avoid a label warning, a segregated line and a recall exposure, which is worth a price premium.
The causal chain runs through labelling law and procurement policy. Regulation (EU) No 1169/2011 sets the mandatory allergen list for the European Union, and soya appears on it while pea does not. US labelling under the Food and Drug Administration follows the nine major food allergens, again excluding pea. Institutional caterers and private-label brand owners increasingly write allergen-exempt protein into tenders, converting a regulatory detail into repeat ingredient volume.
Restraints Impact Analysis
Two constraints hold inclusion rates and margins below what volume growth alone would suggest.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Saponin bitterness and lipid oxidation off-notes limiting dosage | High | Global | Long term ≥4 years |
| Price gap against soy protein isolate compressing processor margins | Medium | Asia Pacific, Latin America | Short term ≤2 years |
Saponin Bitterness and Oxidation Off-Notes Cap Pea Protein Inclusion Rates
Flavour, not protein content, sets the ceiling on how much pea protein a formulator can use. Above roughly a tenth of a beverage formula, most commercial grades deliver a green, bitter, astringent finish that masking systems only partly hide. Brands respond by blending pea with rice, fava or potato protein, which caps the pea share of each recipe and holds back value per litre in the fastest-moving drink formats.
Two chemistries cause it. Saponins B and DDMP in the seed carry an intrinsic bitter and lingering taste, and they concentrate into the protein fraction during isolation. Separately, the pea’s own lipoxygenase acts on residual unsaturated lipids to generate hexanal and related aldehydes, producing the familiar green note that worsens through shelf life. Removing both demands extra washing, enzyme inactivation and low-oxygen drying, each of which raises conversion cost per tonne.
A Persistent Price Gap Against Soy Protein Isolate Compresses Processor Margins
Soy protein isolate remains materially cheaper per unit of protein, and that gap decides most industrial tenders. Where a buyer has no allergen or marketing reason to avoid soy, pea has to win on function or lose the business. The result is thin spreads on commodity-grade concentrate and heavy discounting into animal and pet nutrition, where protein is bought largely on delivered cost per kilogram of crude protein.
The cost sources are specific. Wet fractionation needs isoelectric precipitation, repeated washing, centrifugation and spray drying, so water, effluent treatment and thermal energy dominate conversion cost. Yellow pea itself carries a lower protein content than soybean, so more raw material passes through the plant for each tonne of isolate. A wave of capacity commissioned in North America and Europe also left many lines running well below nameplate, and unabsorbed fixed cost shows up directly in margin.
Market Opportunities
Hydrolysed Pea Fractions Open a Premium Sports and Clinical Nutrition Pool
Enzymatic hydrolysis turns a commodity isolate into a specialty ingredient worth several times the base price. Hydrolysates disperse without grit, stay clear at low pH and avoid much of the viscosity that blocks pea protein from ready-to-drink formats. That combination opens two pools the category has barely touched: clear performance beverages and medical and elderly nutrition, where swallowing ease and amino acid delivery matter more than ingredient cost.
Specialty processors and contract enzyme houses are best placed to capture it, since the value sits in controlling degree of hydrolysis and debittering rather than in milling scale. Demand comes from sports brands building blended protein stacks that pair pea with rice to close the methionine gap, and from hospital and home-care nutrition buyers. Authorised protein claims under Commission Regulation (EU) No 432/2012 apply to any qualifying protein source, which supports label messaging on muscle mass and bone maintenance.
Dry-Fractionated Pea Flours Create a Low-Capex Route Into Pet Food and Bakery
Air classification offers a second business model alongside wet plants, and it opens a revenue pool that isolate producers cannot serve profitably. Dry fractionation mills and air-classifies the pea into protein-enriched and starch-enriched flours at roughly 50% to 60% protein, with no water, no effluent and a fraction of the capital. Output sells into pet food, extruded snacks, bakery and feed, where functional purity matters less than price and clean processing.
Regional millers and cooperatives close to the crop can capture this most easily, because freight on whole pulses is the main cost they avoid. Pet food formulators create much of the demand, valuing the retained native starch and intact flavour profile that wet processing strips out. Bakery users take the same flours for protein enrichment claims. Because the protein keeps its native state, these plant-based protein ingredients also texturise well in low-moisture extrusion.
Segment Analysis
By Product Type: Isolates Lead While Hydrolysates Gain Momentum
Isolates held 47% of pea protein ingredient revenue in 2026, the largest share of any product type, because they are the only grade that reliably clears 80% protein and delivers the gelation and emulsification that meat alternatives and powders require. Concentrates took 28%, textured pea protein 19% and hydrolysates 6%. Hydrolysates are the growth leader at a 13.4% CAGR to 2033, since controlled enzymatic cleavage removes much of the grit and viscosity that keeps standard isolate out of clear beverages. Supporting this shift are better debittering steps, membrane polishing and tighter control of degree of hydrolysis. For the wider market the implication is a widening price ladder: commodity concentrate competes on delivered protein cost, while specialty fractions earn margin on sensory performance and solubility rather than on headline protein content alone.
By Processing Route: Wet Fractionation Dominates as Dry Fractionation Scales Fastest
Wet fractionation accounted for 79% of volume in 2026 because it is the only route that reaches isolate purity and removes enough starch, fibre and anti-nutritional compounds for beverage and meat-alternative use. Dry fractionation holds the remaining 21% but grows fastest at a 13.1% CAGR through 2033. Air classification needs no water, no isoelectric precipitation and no effluent permit, so a regional mill can enter at a small fraction of a wet plant’s capital cost. Native protein functionality also survives milling, which suits low-moisture extrusion and bakery. The commercial implication is a two-tier industry. Wet plants chase high-purity, high-margin grades and depend on selling pea starch co-products to stay viable, while dry lines serve price-led pet food, feed and snack demand with far lower fixed-cost exposure.
By Form: Dry Powders Hold the Base While Liquid Systems Accelerate
Dry powders represented 87% of pea protein ingredient sales in 2026, a dominance explained by freight economics, microbial stability and the fact that most downstream users already handle powder streams. Liquid and pre-dispersed systems hold 13% and expand fastest at a 12.2% CAGR to 2033. Beverage co-packers increasingly buy pre-hydrated, pH-adjusted protein dispersions because in-plant hydration of pea powder is slow, dust-prone and a common source of sediment complaints. Suppliers close to large bottling clusters can ship liquid economically and capture the hydration step as paid value. Spray-dry energy cost adds to the case. The business implication is that form is becoming a service decision rather than a packaging one, and proximity to the customer starts to matter as much as fractionation technology.
By Application: Meat Alternatives Lead as Sports and Active Nutrition Outpaces the Field
Meat alternatives still held the largest application share at 29% in 2026, but the segment is no longer the growth engine it was, as Western patty and ground-style volumes corrected from their peak. Sports and active nutrition, at 23% share, is the fastest-growing application at a 13.6% CAGR through 2033. Dairy alternatives and beverages take 18%, bakery and snacks 12%, pet food 11% and infant and clinical nutrition 7%. Growth has migrated toward blended and hybrid formats that pair textured pea protein with meat, mycoprotein or rice protein rather than replacing meat outright. Protein-fortified bakery, bars and ready-to-mix powders now absorb a rising share of output. For suppliers this means forecasting by recipe inclusion rate, not by plant-based burger unit sales.
Geography Analysis
Which Region Is Leading the Pea Protein Ingredient Market?
North America leads the pea protein ingredient market with 34% revenue share in 2026, built on crop access, processing capacity and the largest sports nutrition consumer base. The prairie provinces of Canada and the northern plains of the United States supply yellow field pea at scale, and several of the world’s largest fractionation plants sit on that crop. Canada is also a major pulse exporter, giving processors flexibility between selling whole peas and fractionating them. Demand is anchored in protein powders, bars, ready-to-mix beverages and pet food rather than in meat analogues alone. The main regional change is consolidation of utilisation: after a build-out that outran demand, operators are filling existing lines and pushing co-product sales of pea starch before approving new capital projects.
Clean-Label Rules and Pulse Cropping Policy Anchor European Demand
Europe holds 31% of pea protein ingredient revenue in 2026, the second-largest position, and it is the most technically demanding region to supply. France, Belgium, Germany, Denmark and the Netherlands host long-established pulse fractionation capability, and the regional crop base benefits from rotation incentives that reward nitrogen-fixing legumes. Buyers apply strict clean-label and additive expectations, which favours pea protein over chemically modified alternatives. Regulation (EU) 2015/2283 on novel foods also matters: conventionally processed pea protein generally sits outside its scope, while newer fractions and processes may require authorisation before launch. The shaping change is scrutiny of environmental marketing, as sustainability and nitrogen-fixation messaging must now satisfy tightening European rules on the substantiation of green claims.
Which Region Is Growing Fastest in the Pea Protein Ingredient Market?
Asia Pacific is growing fastest in the pea protein ingredient market, at a 13.9% CAGR between 2026 and 2033, from a 26% share in 2026. China is both the largest regional processor and the largest consumer, with substantial yellow pea fractionation capacity in Shandong province supplying domestic and export demand. India adds vegetarian protein consumption at scale, Japan and South Korea contribute high-specification sports and clinical nutrition demand, and Australia supplies crop. Cost competitiveness is the regional signature: integrated Chinese producers run large wet lines and sell pea starch into domestic noodle manufacture, which subsidises protein pricing. The change to watch is upgrading, as regional producers move from commodity isolate toward textured and hydrolysed grades for export markets.
Latin America Builds Pea Protein Volume Through Bakery, Feed and Beverage Reformulation
Latin America accounts for 5.5% of pea protein ingredient revenue in 2026 and remains an importing region, with Brazil, Mexico, Chile and Argentina taking most of the volume. Demand concentrates in bakery fortification, dairy-alternative beverages, sports powders and pet food rather than in meat analogues. The central barrier is cost: imported isolate competes against abundant, locally crushed soy protein, and currency movements regularly reset landed price. Tariffs and port logistics add further friction, and technical service for formulators is thin outside the largest cities. The opportunity is reformulation driven by front-of-pack warning labels in several countries, which pushes manufacturers toward higher-protein, lower-sugar recipes and creates pull for functional protein ingredients that carry no allergen declaration.
Middle East & Africa Depends on Imports While Vegetarian and Halal Demand Expands
Middle East & Africa holds 3.5% of pea protein ingredient revenue in 2026, the smallest regional position, and is served almost entirely by imports. The United Arab Emirates, Saudi Arabia, Türkiye, Egypt and South Africa drive most offtake, through sports nutrition retail, bakery manufacture and a growing packaged-food sector. Food security programmes in the Gulf states have put protein self-sufficiency on policy agendas, which supports local blending and packing operations. Barriers are real: limited cold-chain and dry-storage infrastructure, small formulation talent pools, and price sensitivity across most of the continent. The shaping change is halal and vegetarian positioning, since plant protein avoids the certification complexity attached to some animal-derived ingredients and simplifies export between regional markets.
Competitive Landscape
The pea protein ingredient market is moderately concentrated. A small group of integrated fractionators controls most isolate capacity, because a wet plant is a capital-heavy asset that only pays back when protein, starch and fibre all find buyers. Below that tier sits a long tail of dry-fractionation millers, regional cooperatives and traders serving feed, pet food and bakery at lower purity. The build-out of 2019 to 2023 left the industry with more nameplate capacity than current demand absorbs, so competition has shifted from announcing new plants to filling existing ones. Some consolidation of underused assets is expected as weaker independents are absorbed by groups with established co-product channels.
Competition turns on four things rather than on headline protein content: sensory performance, functional consistency between lots, allergen and traceability documentation, and the delivered cost that co-product revenue makes possible. Debittering capability is the clearest technical differentiator, since saponin and lipid-oxidation off-notes decide whether a grade can be used in beverages. New entrants have arrived from two directions. Starch and sweetener processors have extended existing fractionation know-how into pulses, while specialist fermentation and enzyme businesses sell upgrading services such as hydrolysis and off-note removal to incumbents that lack them.
Strategic activity has concentrated on utilisation, formulation support and contracting. Suppliers are opening application laboratories, offering finished blends rather than single ingredients, and signing multi-year grower agreements to secure consistent yellow pea quality. Co-product partnerships matter competitively because a firm starch or fibre contract lets a processor quote protein more aggressively than a rival with the same plant. Several participants have also moved to non-GMO and identity-preserved supply chains to serve European customers.
Strategic direction across the industry points toward quality over volume: better sensory grades, more texturised and hydrolysed fractions, tighter contaminant control, and credible, substantiated sustainability documentation rather than broad environmental claims.
Pea Protein Ingredient Industry Leaders
- Roquette Frères
- Cargill
- Ingredion Incorporated
- PURIS
- Cosucra Groupe Warcoing
Recent Industry Developments
February 2024: The European Union adopted Directive (EU) 2024/825 on empowering consumers for the green transition, which restricts generic environmental claims – it forces pea protein suppliers to substantiate nitrogen-fixation and low-carbon messaging rather than assert it.
June 2023: The EU Deforestation Regulation (EU) 2023/1115 entered into force covering soya among its listed commodities, with application dates subsequently postponed – it raises the compliance burden on soy protein supply chains and strengthens the case for European-grown pulses.
May 2023: Commission Regulation (EU) 2023/915 on maximum levels for certain contaminants became applicable, consolidating earlier limits – it tightens heavy metal and mycotoxin testing obligations across protein ingredient imports.
January 2018: Regulation (EU) 2015/2283 on novel foods became applicable across the European Union – conventionally processed pea protein generally sits outside its scope, while newer fractions and processes may need authorisation before launch.
Pea Protein Ingredient Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 2.6 Billion |
| Market Size 2033 | US$ 5.4 Billion |
| CAGR 2026–2033 | 11.0% |
| Absolute Dollar Opportunity | US$ 2.8 Billion |
| Largest Market | North America, 34% share in 2026 |
| Fastest-Growing Market | Asia Pacific, 13.9% CAGR |
| Market Concentration | Medium |
| Major Players | Roquette Frères, Cargill, Ingredion Incorporated, PURIS, Cosucra Groupe Warcoing |
This study covers global ingredient sales of pea protein isolate, concentrate, textured pea protein and hydrolysates produced from yellow field peas. It excludes whole pulses, pea starch, pea fibre and the retail value of finished consumer products containing pea protein. The base year is 2025, the forecast period runs from 2026 to 2033, and all values are reported in US$ Billion at ingredient selling prices.
Pea Protein Ingredient Market Segmentation
Product Type
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
Processing Route
- Wet Fractionation
- Dry Fractionation
Form
- Dry
- Liquid
Application
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Pea Protein Ingredient Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Pea Starch and Fibre Offtake Is Unlocking Lower-Cost Protein Capacity
- Allergen-Exempt Labelling Is Moving Pea Protein Into Mainstream Food Formats
- Restraints
- Saponin Bitterness and Oxidation Off-Notes Cap Pea Protein Inclusion Rates
- A Persistent Price Gap Against Soy Protein Isolate Compresses Processor Margins
- Market Opportunities
- Hydrolysed Pea Fractions Open a Premium Sports and Clinical Nutrition Pool
- Dry-Fractionated Pea Flours Create a Low-Capex Route Into Pet Food and Bakery
- Drivers
- Global Pea Protein Ingredient Market Outlook, 2020–2033
- Global Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
- Global Pea Protein Ingredient Market Outlook, by Processing Route, Value (US$ Billion), 2020–2033
- Wet Fractionation
- Dry Fractionation
- Global Pea Protein Ingredient Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Dry
- Liquid
- Global Pea Protein Ingredient Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
- Global Pea Protein Ingredient Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Pea Protein Ingredient Market Outlook, 2020–2033
- North America Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
- North America Pea Protein Ingredient Market Outlook, by Processing Route, Value (US$ Billion), 2020–2033
- Wet Fractionation
- Dry Fractionation
- North America Pea Protein Ingredient Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Dry
- Liquid
- North America Pea Protein Ingredient Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
- North America Pea Protein Ingredient Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Canada Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Canada Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Canada Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Canada Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- United States Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- United States Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- United States Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- United States Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- North America Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Pea Protein Ingredient Market Outlook, 2020–2033
- Europe Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
- Europe Pea Protein Ingredient Market Outlook, by Processing Route, Value (US$ Billion), 2020–2033
- Wet Fractionation
- Dry Fractionation
- Europe Pea Protein Ingredient Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Dry
- Liquid
- Europe Pea Protein Ingredient Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
- Europe Pea Protein Ingredient Market Outlook, by Country, Value (US$ Billion), 2020–2033
- France Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- France Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- France Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- France Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Belgium Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Belgium Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Belgium Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Belgium Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Germany Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Germany Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Germany Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Germany Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Denmark Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Denmark Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Denmark Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Denmark Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Netherlands Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Netherlands Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Netherlands Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Netherlands Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Europe Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Pea Protein Ingredient Market Outlook, 2020–2033
- Asia Pacific Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
- Asia Pacific Pea Protein Ingredient Market Outlook, by Processing Route, Value (US$ Billion), 2020–2033
- Wet Fractionation
- Dry Fractionation
- Asia Pacific Pea Protein Ingredient Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Dry
- Liquid
- Asia Pacific Pea Protein Ingredient Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
- Asia Pacific Pea Protein Ingredient Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- China Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- China Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- China Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- India Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- India Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- India Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- India Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Japan Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Japan Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Japan Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Japan Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- South Korea Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- South Korea Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- South Korea Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- South Korea Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Australia Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Australia Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Australia Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Australia Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Asia Pacific Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Pea Protein Ingredient Market Outlook, 2020–2033
- Latin America Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
- Latin America Pea Protein Ingredient Market Outlook, by Processing Route, Value (US$ Billion), 2020–2033
- Wet Fractionation
- Dry Fractionation
- Latin America Pea Protein Ingredient Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Dry
- Liquid
- Latin America Pea Protein Ingredient Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
- Latin America Pea Protein Ingredient Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Brazil Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Brazil Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Brazil Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Mexico Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Mexico Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Mexico Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Mexico Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Chile Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Chile Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Chile Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Chile Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Argentina Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Argentina Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Argentina Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Argentina Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Latin America Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Pea Protein Ingredient Market Outlook, 2020–2033
- Middle East & Africa Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
- Middle East & Africa Pea Protein Ingredient Market Outlook, by Processing Route, Value (US$ Billion), 2020–2033
- Wet Fractionation
- Dry Fractionation
- Middle East & Africa Pea Protein Ingredient Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Dry
- Liquid
- Middle East & Africa Pea Protein Ingredient Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
- Middle East & Africa Pea Protein Ingredient Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- United Arab Emirates Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- United Arab Emirates Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Saudi Arabia Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Saudi Arabia Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Saudi Arabia Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Türkiye Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Türkiye Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Türkiye Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Türkiye Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Egypt Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- Egypt Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- Egypt Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- Egypt Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- South Africa Pea Protein Ingredient Market Outlook, by Product Type, 2020–2033
- South Africa Pea Protein Ingredient Market Outlook, by Processing Route, 2020–2033
- South Africa Pea Protein Ingredient Market Outlook, by Form, 2020–2033
- South Africa Pea Protein Ingredient Market Outlook, by Application, 2020–2033
- Middle East & Africa Pea Protein Ingredient Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Roquette Frères
- Cargill
- Ingredion Incorporated
- Archer Daniels Midland Company
- Kerry Group
- Cosucra Groupe Warcoing
- Emsland Group
- PURIS
- Yantai Shuangta Food Co., Ltd.
- AGT Food and Ingredients
- Axiom Foods, Inc.
- Nutri-Pea Limited
- Vestkorn Milling AS
- Shandong Jianyuan Group
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Isolates
- Concentrates
- Textured Pea Protein
- Hydrolysates
Processing Route
- Wet Fractionation
- Dry Fractionation
Form
- Dry
- Liquid
Application
- Meat Alternatives
- Sports and Active Nutrition
- Dairy Alternatives and Beverages
- Bakery and Snacks
- Pet Food
- Infant and Clinical Nutrition
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global pea protein ingredient market is valued at US$ 2.6 billion in 2026, measured as ingredient sales and excluding finished consumer products made with pea protein.
The market is projected to reach US$ 5.4 billion by 2033, an absolute dollar opportunity of US$ 2.8 billion, growing at an 11.0% CAGR from 2026.
Isolates lead with 47% share in 2026, because only isolate grades reliably deliver the purity, gelation and emulsification that beverage and meat-alternative formulators require.
Sports and active nutrition grows fastest at a 13.6% CAGR through 2033, as blended protein stacks and protein-fortified everyday formats replace single-source powders.
North America holds 34% share in 2026, supported by prairie yellow pea supply, large fractionation capacity and the biggest sports nutrition consumer base.
Related Reports
Coconut Sugar Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the coconut sugar market outlook for 2026–2033, with organic sourcing, product formats, application trends, regional insights, and competition.
Baby Infant Formula Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the baby infant formula market outlook for 2026–2033, including product trends, ingredient bases, regional insights, and competitive analysis.
Margarine Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The margarine market is projected to grow from US$23.5 billion in 2026 to US$27.0 billion by 2033 at a 2.0% CAGR.
Low Fat Cheese Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global low fat cheese market is valued at US$6.8 billion in 2026, reaching US$9.2 billion by 2033, growing at a 4.4% CAGR
Instant Beverage Premix Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global instant beverage premix market is valued at US$24.0 billion in 2026, reaching US$36.5 billion by 2033, growing at a 6.2% CAGR
Infant Nutrition Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global infant nutrition market is valued at US$103.18 billion in 2026, reaching US$153.09 billion by 2033, growing at a 5.8% CAGR