


Warehouse Management System Market
Warehouse Management System Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Warehouse Management System Market Size and Trend Analysis
What drives investment in warehouse management systems?
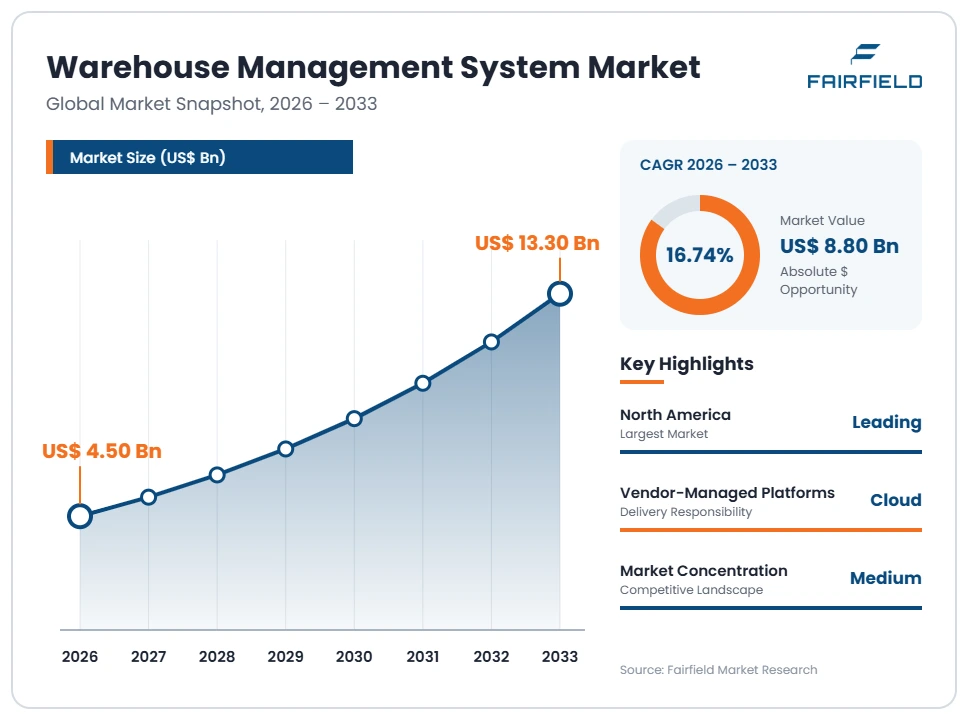
The global Warehouse Management System market size is expected to be valued at US$4.50 billion in 2026 and projected to reach US$13.30 billion by 2033, growing at a CAGR of 16.74% between 2026 and 2033. The commercial opportunity covers software and directly related implementation services supporting warehouse execution. Buyers seek better inventory control, coordinated order processing, and manageable operating costs across increasingly varied fulfillment requirements.
During 2020–2025, warehouse digitization expanded alongside online commerce and distributed fulfillment. A consistent historical CAGR is unavailable; the selected trajectory implies a 2025 value near US$3.85 billion. Replacement of fragmented applications, automation interfaces, and wider network coordination support purchasing. Demand still depends on implementation capacity and usable operational data. Growth should therefore be evaluated through contracted subscriptions, completed deployments, and recognized services rather than inferred directly from warehouse construction or purchases of robots and material-handling equipment.
Key Report Takeaways
- By Operating Model: Owner-Operated Warehouses need execution aligned with their own inventory and orders. Contract Logistics Warehouses require customer-specific rules and reporting. Comparable segment shares and growth rankings are unavailable, so operational complexity is distinguished from measured market leadership.
- By Delivery Responsibility: Vendor-Managed Platforms transfer defined platform operations to the supplier, while Customer-Managed Platforms retain those responsibilities internally. The distinction concerns the contracted operating model rather than a software feature. Buyers should compare upgrade obligations, availability commitments, and integration costs.
- By Purchased Work: Platform Access, Deployment Services, and Continuing Technical Services separate revenue by the purchased deliverable. This avoids repeatedly counting one contract across software and implementation categories. Comparable leadership and fastest-growth rates are not established for this independent taxonomy.
- By Geography: North America leads the selected market benchmark. A consistent fastest-growth ranking is unavailable within the same series. Regional opportunities should be assessed through customer requirements, partner coverage, and implementation capability instead of combining incompatible regional forecasts from different market definitions.
- By Competition: Manhattan Associates, Blue Yonder, Oracle, SAP, and Infor offer directly relevant warehouse software. Competition concerns execution depth, integration, deployment risk, and support. Broader enterprise-software revenue cannot establish a supplier’s share of warehouse management expenditure.
Global Warehouse Management System Market Trends and Insights
Drivers Impact Analysis
Ratings reflect analyst judgement about purchasing mechanisms, without attributing unsupported percentage contributions to the market forecast.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Complex fulfillment and inventory coordination | High | All five standard regions | Short term (≤2 years) |
| Coordinated labor and automation execution | Medium | Automated and expanding warehouses | Medium term (2–4 years) |
Warehouse Management System Demand Follows Fulfillment Complexity
Varied order profiles create demand for software that coordinates inventory, picking, packing, and shipping within one operational process. A warehouse serving stores, business customers, and individual consumers may face different priorities and handling rules during the same shift. Inventory accuracy matters because an incorrect location or stock status can disrupt several downstream tasks. Customers therefore purchase warehouse execution capabilities to resolve identifiable operating problems, rather than simply add another reporting application to existing systems.
Oracle documents warehouse management functions within its logistics portfolio, while Infor offers a dedicated warehouse management system. These products establish direct supplier participation without proving equal suitability universally. Commercial value depends on configuration, master data, and the connection between order demand and physical execution. Buyers should test realistic order mixes and exceptions during evaluation. Suppliers can strengthen proposals through measurable operating objectives, keeping claimed improvements separate from results that require customer-specific implementation and disciplined use.
Warehouse Management System Automation Interfaces Expand Execution Requirements
Automation creates software demand when warehouses need to coordinate workers, storage equipment, and robotic systems around common priorities. Purchasing more machines does not independently solve task allocation or inventory-state problems. Operators need a clear division of responsibilities between warehouse management, execution controls, and equipment software. The commercial requirement is reliable coordination across those interfaces, including exceptions when equipment stops or orders change. This can support additional configuration and integration work alongside the core platform subscription.
Blue Yonder has documented warehouse tasking and robotics-related enhancements, and Manhattan Associates markets warehouse execution within its broader supply-chain portfolio. These offerings illustrate supplier investment in coordination rather than proof that every automated facility needs the same architecture. Customers should establish which system owns each decision and inventory update. Specific value can come from predictable task release and clear exception handling. Integration responsibility, testing, and ongoing version compatibility should be defined before deployment.
Restraints Impact Analysis
Implementation work and transition risk can delay purchasing decisions even where operating problems create a clear business case.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Data migration and enterprise integration | High | Existing multi-system operations | Short term (≤2 years) |
| Operational change and release management | Medium | Complex and multi-site deployments | Medium term (2–4 years) |
Warehouse Management System Integration Raises Project Costs
Integration costs can constrain adoption when a proposed platform must connect orders, inventory, transport, finance, and physical equipment. Existing applications may use inconsistent item identifiers, units, or transaction timing. A new warehouse system cannot automatically resolve those differences. Customers need mapping, reconciliation, interface testing, and clear ownership of data corrections. These activities consume project resources and can postpone the point at which software begins delivering operational value, when partners share deployment responsibility.
The documented breadth of Oracle, SAP, and specialist warehouse offerings makes interface scope a practical procurement issue. Costs arise from migration, configuration, custom connectors, testing environments, and continuing maintenance after connected applications change. Buyers should distinguish standard integration capabilities from work still required for their environment. Suppliers and integrators can reduce uncertainty through an agreed architecture and acceptance criteria. Project budgets should include implementation and stabilization, rather than treating a quoted license or subscription as the complete investment.
Warehouse Management System Cutovers Require Operational Readiness
Transition risk can limit adoption because warehouse operations must continue while staff learn new processes and inventory records move to another system. A poorly prepared cutover can affect receiving, order release, shipping, and customer service. Purchasing committees may therefore delay an otherwise attractive replacement until operating teams can support testing and training. This is a capacity constraint on implementation, not evidence that the underlying software lacks useful functions or modernization is unnecessary.
Costs include temporary parallel processes, user training, inventory checks, contingency planning, and support during stabilization. Release management also matters after launch, especially when interfaces or configured workflows need retesting. Vendor-managed delivery changes some responsibilities but does not remove customer process ownership. Buyers should establish rollback options and operating acceptance tests before committing to dates. Suppliers can support adoption through staged deployment and clear escalation arrangements, linking project milestones to demonstrated readiness rather than a calendar commitment alone.
Market Opportunities
Warehouse Management System Retrofit Projects Can Monetize Integration Gaps
Existing warehouses create opportunities for targeted modernization where operators need better execution without replacing every application or physical asset. Projects may address inventory visibility, customer onboarding, task coordination, or specific automation interfaces. Suppliers can earn configuration, implementation, and continuing support revenue around a clearly defined operational gap. This differs from selling replacement solely because software is old. The purchasing case depends on measurable problems and a feasible route to change.
Specialist software vendors and implementation partners can pursue customers with fragmented workflows or newly introduced equipment. Blue Yonder’s agreement with GXO provides a documented example of a logistics operator establishing a preferred software relationship. Such arrangements support repeatable delivery, but do not establish a universal implementation template. Providers should assess existing interfaces and customer rules before scope commitment. Staged projects can create a practical entry point when customers lack resources or time for a wider cutover.
Warehouse Management System Network Rollouts Create Repeatable Services
Multi-site rollouts create opportunities to reuse a tested operational design across warehouses with sufficiently similar requirements. Customers may seek consistent inventory definitions, reporting, configuration governance, and support arrangements. Suppliers can capture additional platform access and rollout services as sites enter the program. The commercial value lies in reducing repeated design work while preserving necessary local differences. A common product alone does not establish that every warehouse can operate with identical processes or implementation effort.
Manhattan Associates’ commercial launch of Editions in September 2026 illustrates an effort to package capabilities for different stages of customer growth. The announcement is relevant to accessibility and deployment choices, not proof of a specific cost saving. Vendors and partners can pursue growing operators that need a repeatable expansion model. Contracts should separate reusable platform capabilities from site-specific integration and training. This helps buyers assess the economics of each additional location without assuming initial complexity disappears .
Segment Analysis
- By Operating Model: Warehouse Management System Customer Rules Shape Configuration
Owner-Operated Warehouses principally execute inventory and order requirements for the owning business. Contract Logistics Warehouses execute services for external clients, potentially with different billing, handling, and reporting rules. Classification follows the warehouse’s contracted operating model rather than the sector of every stored product. This makes the categories commercially usable and prevents the same facility from being counted repeatedly because it handles several merchandise types or order channels.
Comparable shares and growth rankings are unavailable for this segmentation. Contract logistics buyers may prioritize client onboarding and segregated reporting, while owner-operated facilities may emphasize integration with production or retail operations. Those priorities require customer validation. Blue Yonder’s documented GXO relationship confirms a relevant logistics purchasing context. Suppliers should demonstrate realistic customer-rule changes and exception handling. Buyers benefit from evaluating operating complexity and implementation effort rather than assuming the largest floor area or transaction count automatically identifies the most attractive software opportunity.
- By Delivery Responsibility: Warehouse Management System Operations Need Clear Ownership
Vendor-Managed Platforms place defined hosting and platform-operation responsibilities with the supplier. Customer-Managed Platforms retain those duties within the customer’s operating arrangement. Classification follows contractual responsibility, avoiding overlap between deployment terminology and ownership of daily technical tasks. Oracle, Manhattan Associates, and Infor document cloud-oriented warehouse offerings, while other deployment choices require examination of the specific product and contract. Product availability should not be confused with a measured segment share.
A consistent leader and fastest-growth rate are unavailable for this independent axis. Buyers should compare upgrade testing, access controls, availability, integration, and data-management obligations. Vendor-managed delivery can change internal staffing needs while retaining substantial customer responsibilities for processes and interfaces. Customer-managed delivery requires appropriate technical capacity and maintenance planning. Suppliers should explain the actual service boundary and ongoing charges. That makes comparisons more useful than assuming one delivery label guarantees lower lifetime cost or removes implementation risk in every warehouse environment.
- By Purchased Work: Warehouse Management System Contracts Contain Distinct Revenue Pools
Platform Access covers software licenses or subscriptions attributable to warehouse management. Deployment Services covers initial configuration, migration, integration, and training. Continuing Technical Services includes separately purchased maintenance and technical support after deployment. Each revenue item is assigned by its primary deliverable, preventing the complete contract from being counted in several categories. Physical equipment and unrelated enterprise modules remain outside the boundary even when sold by the same commercial group.
Comparable shares and fastest-growth rates are unavailable for these definitions. The distinction is still important because project revenue can rise during a rollout while recurring platform revenue follows a different recognition pattern. Suppliers should report those movements separately, and buyers should identify which costs recur. Manhattan Associates, Blue Yonder, and enterprise-suite vendors offer relevant capabilities, but their wider portfolios do not establish warehouse-specific revenue. Commercial analysis should therefore connect a defined deliverable with its contracted price, deployment stage, and continuing obligations.
Geography Analysis
- Which Region Is Leading the Warehouse Management System Market?
North America leads the selected benchmark outlook, supported by established software purchasing and complex distribution operations. The United States and Canada are relevant customer settings, with specialist and enterprise-suite suppliers serving varied warehouse needs. Manhattan Associates, Oracle, and Blue Yonder provide documented commercial offerings. Their presence establishes supplier access, rather than a current national share or a guaranteed purchasing advantage for every customer.
Opportunities include platform replacement, automation interfaces, and coordinated network rollouts. Implementation capacity, data quality, and operating disruption remain constraints. Suppliers should assess actual customer workflows and local partner coverage. Buyers should compare complete deployment and support requirements, because a broad regional software ecosystem does not remove the work needed to stabilize an individual warehouse installation.
- Warehouse Management System European Projects Need Local Process Fit
Europe offers warehouse software opportunities across retail distribution, manufacturing, and contract logistics. Germany, France, and the United Kingdom provide relevant customer-development settings. SAP’s warehouse offering and the international presence of specialist vendors establish available supply options. Comparable national shares are not adopted here. Requirements differ by customer network, labor processes, system estate, and the degree of automation within each site.
Opportunities include repeatable configurations and targeted replacement of fragmented applications. Buyers need clear interface responsibilities and suitable local implementation support. Suppliers should assess language, reporting, and operational requirements without assuming one national template covers the region. A phased deployment can be appropriate where warehouses have different cutover windows. Commercial attractiveness depends on executable projects and recurring use, rather than warehouse floor space alone.
- Which Region Is Growing Fastest in Warehouse Management Systems?
A consistent fastest-growing region is not established within the selected benchmark series; Asia Pacific remains a relevant expansion setting. China, India, Japan, and Australia contain distinct manufacturing, retail, and logistics customer environments. Their warehouse requirements differ in scale, existing applications, and implementation resources. No regional forecast rate or country ranking is inferred from general e-commerce activity or announced logistics construction.
Suppliers can pursue customer onboarding, inventory control, and automation integration where an actual operating need is documented. Local partner capacity and support arrangements affect delivery economics. Buyers should establish the scope of platform access, configuration, and continuing services before comparing offers. The opportunity is strongest when software resolves measurable workflow problems and the customer has sufficient data and operating resources to complete implementation.
- Warehouse Management System Latin American Growth Requires Deployment Support
Latin America offers selective opportunities for modernizing warehouse execution and coordinating distribution networks. Brazil, Mexico, and Chile provide useful customer-development settings without establishing a verified ranking. Operators may need more reliable inventory records, client reporting, or order handling. Those requirements should be identified directly rather than inferred from a broad increase in industrial activity or the number of new logistics properties.
Constraints include project budgets, integration resources, and access to continuing technical support. Suppliers can work with qualified regional partners to provide configuration and training. Opportunities include staged rollouts and improvements within existing facilities. Buyers should compare recurring charges, implementation work, and support coverage together. A manageable initial scope can help establish operating confidence before a customer commits to a wider warehouse network program.
- Warehouse Management System Middle East & Africa Needs Focused Integration
Middle East & Africa presents opportunities in distribution, contract logistics, and industrial warehousing. The United Arab Emirates, Saudi Arabia, and South Africa are relevant customer settings. These examples do not establish market-share leadership. A new logistics project creates potential software demand only when its operating model, order processes, and integration requirements are sufficiently defined for procurement and implementation.
Barriers include limited project resources, variable connectivity, and uneven access to specialist support. Suppliers can pursue focused installations through partners able to maintain local operating relationships. Opportunities include coordinated inventory execution and client-specific reporting. Buyers should clarify interfaces, training, and responsibilities after launch. A credible proposal connects the software with a usable workflow and continuing support rather than treating a regional infrastructure announcement as automatically recognized warehouse management revenue.
Competitive Landscape
Competition spans specialist warehouse vendors and broader enterprise-software suppliers. Medium concentration is an analyst judgement reflecting several established global platforms alongside regional and specialist alternatives. Manhattan Associates, Blue Yonder, Oracle, SAP, and Infor have verified warehouse-related offerings. Their complete supply-chain or enterprise revenues are not comparable warehouse management shares. Buyers should assess the specific software and service scope, particularly when a proposal combines warehouse execution with transport, planning, commerce, or equipment integration.
The basis of competition includes workflow depth, configuration flexibility, implementation risk, partner capacity, and continuing support. New entrants can address narrower operating needs, but must establish dependable interfaces and support during live warehouse operations. Established suppliers also face scrutiny when broader functionality increases deployment effort. A product demonstration is insufficient if the customer cannot reconcile inventory, manage exceptions, or maintain the configuration after connected applications change.
Documented moves show attention to both technology and commercial delivery. Blue Yonder established a strategic relationship with GXO in May 2025. Manhattan Associates announced agentic capabilities that month and commercially launched Editions in September 2026. These developments concern preferred supplier access, product functionality, and packaging. They do not prove equivalent customer adoption or independently measured productivity gains across warehouses.
Strategic differentiation should connect a defined operating problem with an executable deployment. Suppliers can improve proposals through clear responsibilities, realistic acceptance tests, and transparent recurring charges. Buyers should compare software, implementation, and support separately, while assessing the combined operating model. Competitive analysis is more useful when it follows verified capabilities and project execution than when it assigns rankings from unrelated revenues or predicts which platform will dominate future warehouse investment.
Recent Industry Developments
- May 2025: Blue Yonder and GXO announced a strategic global agreement, including a preferred warehouse-software relationship supporting implementations.
- May 2025: Manhattan Associates announced agentic capabilities for Manhattan Active, expanding its product-development direction across supply-chain execution.
- September 2026: Manhattan Associates commercially launched Editions for Manhattan Active solutions, providing packaged choices for customers at different growth stages.
Companies Covered in the Report
Manhattan Associates; Blue Yonder; Oracle; SAP; Infor; GXO. GXO is discussed as a logistics customer and commercial partner, rather than ranked as a warehouse software vendor.
Warehouse Management System Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$4.50 Billion |
| Market Size 2033 | US$13.30 Billion |
| CAGR 2026–2033 | 16.74% |
| Absolute Dollar Opportunity | US$8.80 Billion |
| Largest Market | North America, selected benchmark |
| Fastest-Growing Market | Not consistently established for this benchmark |
| Market Concentration | Medium, analyst judgement |
| Major Players | Manhattan Associates, Blue Yonder, Oracle, SAP, Infor |
Warehouse Management System Market Segmentation
Operating Model
- Owner-Operated Warehouses
- Contract Logistics Warehouses
Delivery Responsibility
- Vendor-Managed Platforms
- Customer-Managed Platforms
Purchased Work
- Platform Access
- Deployment Services
- Continuing Technical Services
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Warehouse Management System Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Warehouse Management System Demand Follows Fulfillment Complexity
- Warehouse Management System Automation Interfaces Expand Execution Requirements
- Restraints
- Warehouse Management System Integration Raises Project Costs
- Warehouse Management System Cutovers Require Operational Readiness
- Market Opportunities
- Warehouse Management System Retrofit Projects Can Monetize Integration Gaps
- Warehouse Management System Network Rollouts Create Repeatable Services
- Drivers
- Global Warehouse Management System Market Outlook, 2020–2033
- Global Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Owner-Operated Warehouses
- Contract Logistics Warehouses
- Global Warehouse Management System Market Outlook, by Delivery Responsibility, Value (US$ Billion), 2020–2033
- Vendor-Managed Platforms
- Customer-Managed Platforms
- Global Warehouse Management System Market Outlook, by Purchased Work, Value (US$ Billion), 2020–2033
- Platform Access
- Deployment Services
- Continuing Technical Services
- Global Warehouse Management System Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- North America Warehouse Management System Market Outlook, 2020–2033
- North America Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Owner-Operated Warehouses
- Contract Logistics Warehouses
- North America Warehouse Management System Market Outlook, by Delivery Responsibility, Value (US$ Billion), 2020–2033
- Vendor-Managed Platforms
- Customer-Managed Platforms
- North America Warehouse Management System Market Outlook, by Purchased Work, Value (US$ Billion), 2020–2033
- Platform Access
- Deployment Services
- Continuing Technical Services
- North America Warehouse Management System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- United States Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- United States Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Canada Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Canada Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Canada Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- North America Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Europe Warehouse Management System Market Outlook, 2020–2033
- Europe Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Owner-Operated Warehouses
- Contract Logistics Warehouses
- Europe Warehouse Management System Market Outlook, by Delivery Responsibility, Value (US$ Billion), 2020–2033
- Vendor-Managed Platforms
- Customer-Managed Platforms
- Europe Warehouse Management System Market Outlook, by Purchased Work, Value (US$ Billion), 2020–2033
- Platform Access
- Deployment Services
- Continuing Technical Services
- Europe Warehouse Management System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Germany Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Germany Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- France Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- France Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- France Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- United Kingdom Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- United Kingdom Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- United Kingdom Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Europe Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Asia Pacific Warehouse Management System Market Outlook, 2020–2033
- Asia Pacific Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Owner-Operated Warehouses
- Contract Logistics Warehouses
- Asia Pacific Warehouse Management System Market Outlook, by Delivery Responsibility, Value (US$ Billion), 2020–2033
- Vendor-Managed Platforms
- Customer-Managed Platforms
- Asia Pacific Warehouse Management System Market Outlook, by Purchased Work, Value (US$ Billion), 2020–2033
- Platform Access
- Deployment Services
- Continuing Technical Services
- Asia Pacific Warehouse Management System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- China Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- China Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- India Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- India Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- India Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Japan Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Japan Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Japan Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Australia Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Australia Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Australia Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Asia Pacific Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Latin America Warehouse Management System Market Outlook, 2020–2033
- Latin America Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Owner-Operated Warehouses
- Contract Logistics Warehouses
- Latin America Warehouse Management System Market Outlook, by Delivery Responsibility, Value (US$ Billion), 2020–2033
- Vendor-Managed Platforms
- Customer-Managed Platforms
- Latin America Warehouse Management System Market Outlook, by Purchased Work, Value (US$ Billion), 2020–2033
- Platform Access
- Deployment Services
- Continuing Technical Services
- Latin America Warehouse Management System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Brazil Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Brazil Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Mexico Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Mexico Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Mexico Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Chile Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Chile Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Chile Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Latin America Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Middle East & Africa Warehouse Management System Market Outlook, 2020–2033
- Middle East & Africa Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Owner-Operated Warehouses
- Contract Logistics Warehouses
- Middle East & Africa Warehouse Management System Market Outlook, by Delivery Responsibility, Value (US$ Billion), 2020–2033
- Vendor-Managed Platforms
- Customer-Managed Platforms
- Middle East & Africa Warehouse Management System Market Outlook, by Purchased Work, Value (US$ Billion), 2020–2033
- Platform Access
- Deployment Services
- Continuing Technical Services
- Middle East & Africa Warehouse Management System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- United Arab Emirates Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- United Arab Emirates Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Saudi Arabia Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- Saudi Arabia Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- Saudi Arabia Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- South Africa Warehouse Management System Market Outlook, by Operating Model, 2020–2033
- South Africa Warehouse Management System Market Outlook, by Delivery Responsibility, 2020–2033
- South Africa Warehouse Management System Market Outlook, by Purchased Work, 2020–2033
- Middle East & Africa Warehouse Management System Market Outlook, by Operating Model, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Manhattan Associates
- Blue Yonder
- Oracle
- SAP
- Infor
- GXO
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Operating Model
- Owner-Operated Warehouses
- Contract Logistics Warehouses
Delivery Responsibility
- Vendor-Managed Platforms
- Customer-Managed Platforms
Purchased Work
- Platform Access
- Deployment Services
- Continuing Technical Services
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Warehouse Management System Market is estimated at US$4.50 billion in 2026, covering warehouse execution software and directly related deployment and technical services.
The market is projected to reach US$13.30 billion by 2033, implying 16.74% annual growth and US$8.80 billion additional opportunity within the defined scope.
A comparable operating-model leader is unavailable; Owner-Operated Warehouses and Contract Logistics Warehouses have different configuration requirements, without consistent published shares for this taxonomy.
A consistent fastest-growth region is unavailable in the selected benchmark; regional opportunity depends on customer workflows, implementation resources, partner coverage, and actual deployment activity.
North America leads the selected benchmark outlook, supported by established software purchasing and complex distribution operations, although a consistent current regional percentage is unavailable.
Related Reports
Electric Vehicle Sound Generator Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Electric vehicle sound generator market to grow from US$1.2 Bn in 2026 to US$3.2 Bn by 2033 at 15.0% CAGR. Explore systems, components and regions.
On-Demand Warehousing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On-demand warehousing market to grow from US$17.20 Bn in 2026 to US$47.51 Bn by 2033 at 15.6% CAGR. Explore services, storage duration and regional trends.
On-Demand Trucking Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On-demand trucking market to grow from US$11.00 Bn in 2026 to US$30.52 Bn by 2033 at 15.7% CAGR. Explore truck types, services, industries and regions.
On-Demand Transportation Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On-demand transportation market to grow from US$289.18 Bn in 2026 to US$779.10 Bn by 2033 at 15.2% CAGR. Explore services, vehicles and regional trends.
On-Board Diagnostics (OBD) Aftermarket Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On-board diagnostics (OBD) aftermarket to grow from US$4.74 Bn in 2026 to US$21.02 Bn by 2033 at 23.7% CAGR. Explore connectivity, applications and regions.
On-Board Charger Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On-board charger market to grow from US$10.13 Bn in 2026 to US$27.16 Bn by 2033 at 15.1% CAGR. Explore propulsion, power output, vehicles and regions.