


Data-Centric Security Market
Data-Centric Security Market Insights, Competitive Landscape, and Market Forecast - 2033
Market Overview
Data-centric security shifts cybersecurity focus from protecting network perimeters toward protecting the data itself through encryption, access governance, and loss prevention technology that travels with data regardless of where it resides or how it moves across increasingly distributed and cloud-based IT environments. As traditional network perimeter-based security models have become less effective amid widespread cloud adoption, remote work, and complex multi-vendor data ecosystems, organizations have increasingly prioritized security approaches that protect data assets directly.
Demand growth through the 2026-2033 window is closely tied to accelerating enterprise cloud adoption dissolving traditional network security perimeters and requiring data-level protection approaches, intensifying data privacy regulation across major markets requiring demonstrable data protection and governance capability, and rising data breach frequency and cost driving organizational prioritization of comprehensive data protection strategies. Growing enterprise recognition that data itself, rather than network infrastructure alone, represents the primary asset requiring protection continues to reshape cybersecurity investment priorities.
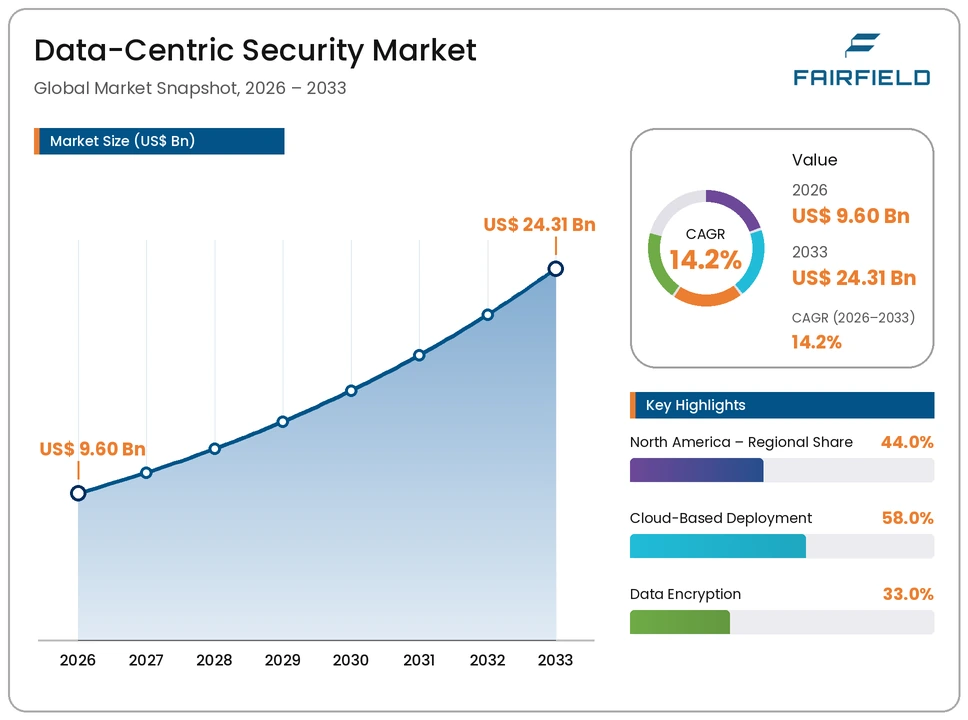
The market is valued at USD 9.60 Billion in 2026, with providers directing substantial investment toward unified data protection platforms that combine encryption, access governance, and loss prevention capability across increasingly complex, distributed data environments. By 2033, the market is forecast to reach USD 24.31 Billion, reflecting steady growth across established data encryption applications alongside expanding hybrid deployment adoption.
Key Highlights
- The global data-centric security market is valued at USD 9.60 Billion in 2026 and is projected to reach USD 24.31 Billion by 2033, expanding at a CAGR of 14.2% across the 2026-2033 forecast period.
- Data Encryption leads the solution-type segment with a 33.0% share in 2026, equivalent to USD 3.17 Billion.
- Cloud-Based deployment remains the dominant deployment mode, accounting for 58.0% of global demand, or USD 5.57 Billion, in 2026.
- North America commands the largest regional share at 44.0% of the global market in 2026.
- Hybrid deployment configurations are emerging as the fastest-growing deployment mode through 2033.
Key Growth Drivers
Growth in the data-centric security market is driven primarily by accelerating enterprise cloud adoption, as organizations increasingly distribute data across multiple cloud platforms and services, dissolving traditional network perimeters and requiring security approaches that protect data directly regardless of its location or the infrastructure hosting it.
A second driver is intensifying data privacy regulation across major markets, as expanding regulatory requirements for data protection and governance create direct compliance incentive for organizations to implement comprehensive data-centric security capability demonstrating regulatory accountability.
Key Restraints
The technical complexity of implementing comprehensive data-centric security across diverse, often legacy data systems and formats creates significant implementation challenges, requiring substantial technical investment to achieve consistent protection across an organization's full data estate.
Additionally, data classification and discovery challenges, particularly for organizations with large volumes of unstructured data across numerous systems, create a foundational obstacle to effective data-centric security implementation, as organizations must first understand what data they hold before they can protect it effectively.
Market Opportunities
The expansion of hybrid deployment configurations presents a substantial opportunity, as organizations increasingly operate data across both cloud and on-premises environments, creating demand for data-centric security solutions capable of providing consistent protection and governance across these hybrid architectures.
A second opportunity lies in the continued development of automated data discovery and classification technology that reduces the manual effort required to identify and appropriately protect sensitive data across complex enterprise environments. Providers that successfully advance these automation capabilities stand to capture growing demand as organizations seek more efficient paths to comprehensive data protection.
Segmentation Analysis
- By Solution Type
Data Encryption leads the solution-type segment, accounting for 33.0% of global market value in 2026, equivalent to USD 3.17 Billion. Its leadership reflects encryption's foundational role in protecting data confidentiality across storage, transit, and processing states. Data Loss Prevention (DLP) represents a significant, established solution-type category. Data Access Governance represents the fastest-growing solution-type category through 2033, driven by growing regulatory emphasis on demonstrable data access control and accountability.
- By Deployment Mode
Cloud-Based deployment forms the leading deployment-mode segment, representing 58.0% of global demand in 2026, or USD 5.57 Billion, reflecting the broader enterprise shift toward cloud infrastructure requiring correspondingly cloud-native data protection approaches. On-Premises deployment continues to serve organizations with specific data residency requirements. Hybrid deployment represents the fastest-growing deployment-mode category, propelled by organizations operating data across both cloud and on-premises environments.
Regional Insights
- North America
North America holds the largest regional share, at 44.0% of the global market in 2026, equivalent to USD 4.22 Billion. The region's leadership reflects high enterprise cybersecurity investment maturity and stringent data privacy regulatory requirements across the United States and Canada.
- Europe
Europe accounts for 27.0% of the global market in 2026, valued at USD 2.59 Billion. Demand is supported by comprehensive data privacy regulation, including the General Data Protection Regulation, requiring robust data protection capability across major European markets.
- Asia Pacific
Asia Pacific represents 21.0% of the global market in 2026, or USD 2.02 Billion. Growth is underpinned by rapidly expanding cloud adoption and increasing data privacy regulation across China, India, and Japan.
- Latin America
Latin America contributes 5.0% of the global market in 2026, equivalent to USD 0.48 Billion. Growth is linked to expanding cybersecurity investment and growing data privacy regulation in Brazil and Mexico.
- Middle East & Africa
Middle East & Africa holds 3.0% of the global market in 2026, valued at USD 0.29 Billion. Growth remains gradual, tied to expanding cybersecurity investment across the region.
Competitive Landscape
The global data-centric security market is moderately fragmented, with a mix of large diversified cybersecurity companies and specialized data protection vendors competing for enterprise adoption. Competition centers on breadth of data protection capability spanning encryption, access governance, and loss prevention, integration across diverse cloud and on-premises data environments, and the ability to support automated data discovery and classification at scale. Companies are increasingly differentiating through unified platform capability rather than competing on point-solution pricing alone.
Key Market Players
- Microsoft Corporation
- IBM Corporation
- Broadcom Inc.
- Thales Group
- Varonis Systems, Inc.
- Informatica Inc.
- Netskope, Inc.
- Fortra, LLC
- OpenText Corporation
- Forcepoint LLC
Market Segmentation
By Solution Type
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
By Deployment Mode
- Cloud-Based
- On-Premises
- Hybrid
By Organization Size
- Large Enterprises
- Small & Medium Enterprises
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Data-Centric Security Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Data-Centric Security Market Outlook, 2020 - 2033
- Global Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Large Enterprises
- Small & Medium Enterprises
- Global Data-Centric Security Market Outlook, by Deployment Mode, Value (US$ Mn), 2020-2033
- Cloud-Based
- On-Premises
- Hybrid
- Global Data-Centric Security Market Outlook, by Solution Type, Value (US$ Mn), 2020-2033
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
- Global Data-Centric Security Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- North America Data-Centric Security Market Outlook, 2020 - 2033
- North America Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Large Enterprises
- Small & Medium Enterprises
- North America Data-Centric Security Market Outlook, by Deployment Mode, Value (US$ Mn), 2020-2033
- Cloud-Based
- On-Premises
- Hybrid
- North America Data-Centric Security Market Outlook, by Solution Type, Value (US$ Mn), 2020-2033
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
- North America Data-Centric Security Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- U.S. Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- U.S. Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Canada Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Canada Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Canada Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Europe Data-Centric Security Market Outlook, 2020 - 2033
- Europe Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Large Enterprises
- Small & Medium Enterprises
- Europe Data-Centric Security Market Outlook, by Deployment Mode, Value (US$ Mn), 2020-2033
- Cloud-Based
- On-Premises
- Hybrid
- Europe Data-Centric Security Market Outlook, by Solution Type, Value (US$ Mn), 2020-2033
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
- Europe Data-Centric Security Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Germany Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Germany Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Italy Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Italy Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Italy Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- France Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- France Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- France Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- U.K. Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- U.K. Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- U.K. Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Spain Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Spain Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Spain Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Russia Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Russia Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Russia Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Rest of Europe Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Rest of Europe Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Rest of Europe Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Asia Pacific Data-Centric Security Market Outlook, 2020 - 2033
- Asia Pacific Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Large Enterprises
- Small & Medium Enterprises
- Asia Pacific Data-Centric Security Market Outlook, by Deployment Mode, Value (US$ Mn), 2020-2033
- Cloud-Based
- On-Premises
- Hybrid
- Asia Pacific Data-Centric Security Market Outlook, by Solution Type, Value (US$ Mn), 2020-2033
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
- Asia Pacific Data-Centric Security Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- China Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- China Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Japan Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Japan Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Japan Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- South Korea Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- South Korea Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- South Korea Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- India Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- India Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- India Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Southeast Asia Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Southeast Asia Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Southeast Asia Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Rest of SAO Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Rest of SAO Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Rest of SAO Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Latin America Data-Centric Security Market Outlook, 2020 - 2033
- Latin America Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Large Enterprises
- Small & Medium Enterprises
- Latin America Data-Centric Security Market Outlook, by Deployment Mode, Value (US$ Mn), 2020-2033
- Cloud-Based
- On-Premises
- Hybrid
- Latin America Data-Centric Security Market Outlook, by Solution Type, Value (US$ Mn), 2020-2033
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
- Latin America Data-Centric Security Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Brazil Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Brazil Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Mexico Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Mexico Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Mexico Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Argentina Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Argentina Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Argentina Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Rest of LATAM Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Rest of LATAM Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Rest of LATAM Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Middle East & Africa Data-Centric Security Market Outlook, 2020 - 2033
- Middle East & Africa Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Large Enterprises
- Small & Medium Enterprises
- Middle East & Africa Data-Centric Security Market Outlook, by Deployment Mode, Value (US$ Mn), 2020-2033
- Cloud-Based
- On-Premises
- Hybrid
- Middle East & Africa Data-Centric Security Market Outlook, by Solution Type, Value (US$ Mn), 2020-2033
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
- Middle East & Africa Data-Centric Security Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- GCC Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- GCC Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- South Africa Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- South Africa Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- South Africa Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Egypt Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Egypt Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Egypt Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Nigeria Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Nigeria Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Nigeria Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- Rest of Middle East Data-Centric Security Market Outlook, by Organization Size, 2020-2033
- Rest of Middle East Data-Centric Security Market Outlook, by Deployment Mode, 2020-2033
- Rest of Middle East Data-Centric Security Market Outlook, by Solution Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Data-Centric Security Market Outlook, by Organization Size, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Microsoft Corporation
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- IBM Corporation
- Broadcom Inc.
- Thales Group
- Varonis Systems, Inc.
- Informatica Inc.
- Netskope, Inc.
- Fortra, LLC
- OpenText Corporation
- Forcepoint LLC
- Microsoft Corporation
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Solution Type
- Data Encryption
- Data Loss Prevention (DLP)
- Data Access Governance
- Others
By Deployment Mode
- Cloud-Based
- On-Premises
- Hybrid
By Organization Size
- Large Enterprises
- Small & Medium Enterprises
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global data-centric security market is valued at USD 9.60 Billion in 2026, reflecting the shift from network perimeter to data-level security approaches.
The market is projected to grow at a CAGR of 14.2%, reaching USD 24.31 Billion by 2033, driven by cloud adoption and intensifying data privacy regulation.
Data Encryption leads with a 33.0% share in 2026, reflecting its foundational role in protecting data confidentiality.
North America leads with a 44.0% share in 2026, supported by high cybersecurity investment maturity and stringent data privacy requirements.
The largest opportunity lies in hybrid deployment configurations, expanding as organizations manage data across both cloud and on-premises environments.
Related Reports
Smart Home Appliances Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the smart home appliances market, reaching US$ 113.0 billion by 2033 at 13.0% CAGR, with product, regional and competitive insights.
Smart Cities Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the smart cities market, reaching US$ 420.0 billion by 2033 at 12.7% CAGR, with solution, regional and competitive insights.
Industrial Robotics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the industrial robotics market, reaching US$ 95.0 billion by 2033 at 8.4% CAGR, with robot types, regional and competitive insights.
Holographic Display Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the holographic display market, reaching US$ 7.6 billion by 2033 at 17.9% CAGR, with technology, regional and competitive insights.
Gas Sensors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the gas sensors market, forecast to reach US$ 4.7 billion by 2033 at 8.8% CAGR, with technology, regional and competitive insights.
Cybersecurity Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Cybersecurity market to reach US$ 525.0 billion by 2033 at 11.3% CAGR. Explore security types, regional trends and key companies.