


Fire Protection System Pipes Market
Fire Protection System Pipes Market Insights, Competitive Landscape, and Market Forecast 2033
Market Overview
Fire protection system pipes encompass the piping infrastructure used within sprinkler, standpipe, and other fire suppression systems, spanning CPVC, steel, and increasingly HDPE materials engineered to reliably deliver water or fire suppression agents throughout building fire safety infrastructure. As building safety regulatory requirements have continued strengthening globally alongside growing construction activity across commercial and residential sectors, fire protection piping has become an increasingly essential component of modern building infrastructure investment.
Demand growth through the 2026-2033 window is closely tied to sustained global commercial and residential construction activity requiring fire protection system installation, growing building safety regulatory enforcement mandating fire suppression system installation across an expanding range of building types, and continued material technology advancement improving installation efficiency and corrosion resistance performance. Growing building retrofit and fire safety system upgrade activity continues to support demand beyond new construction applications alone.
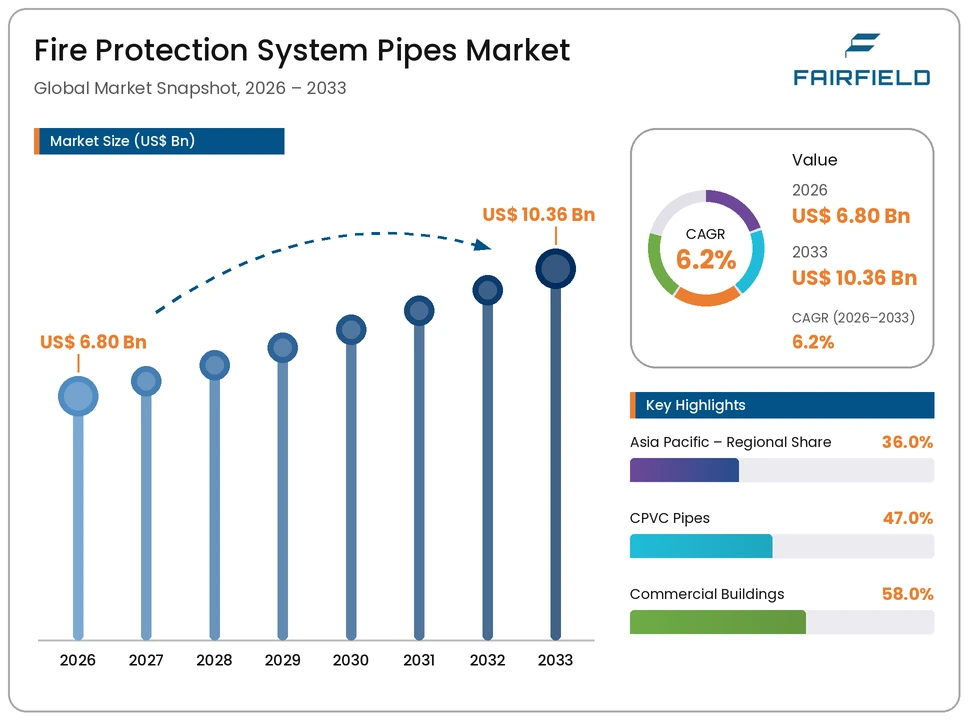
The market is valued at USD 6.80 Billion in 2026, with manufacturers directing investment toward improved material technology that enhances installation efficiency and long-term system reliability. By 2033, the market is forecast to reach USD 10.36 Billion, reflecting steady growth across established CPVC pipe applications alongside expanding HDPE pipe adoption.
Key Highlights
- The global fire protection system pipes market is valued at USD 6.80 Billion in 2026 and is projected to reach USD 10.36 Billion by 2033, expanding at a CAGR of 6.2% across the 2026-2033 forecast period.
- CPVC Pipes lead the material-type segment with a 47.0% share in 2026, equivalent to USD 3.20 Billion.
- Commercial Buildings remain the dominant end-use segment, accounting for 58.0% of global demand, or USD 3.94 Billion, in 2026.
- Asia Pacific commands the largest regional share at 36.0% of the global market in 2026.
- HDPE pipes are emerging as the fastest-growing material-type category through 2033.
Market Dynamics
Key Growth Drivers
Growth in the fire protection system pipes market is driven primarily by sustained global commercial and residential construction activity, as continued building development across major construction markets drives consistent demand for fire protection system installation.
A second driver is growing building safety regulatory enforcement, as governments worldwide continue strengthening fire suppression system installation requirements across an expanding range of commercial and residential building types.
Key Restraints
Raw material price volatility associated with both plastic resin and steel piping materials creates cost management challenges for manufacturers, as material pricing fluctuations directly affect production economics and project cost competitiveness.
Additionally, varying regional building code and fire safety certification requirements create compliance complexity for manufacturers, as piping products must satisfy differing performance and certification standards across global markets.
Market Opportunities
The expansion of HDPE pipe adoption presents a substantial opportunity, as growing preference for corrosion-resistant, lightweight piping materials continues to expand HDPE's market position relative to conventional steel and CPVC alternatives.
A second opportunity lies in continued material innovation that further improves installation efficiency and system reliability. Companies that successfully advance this material technology stand to capture growing demand as building developers continue prioritizing both installation cost efficiency and long-term fire protection system performance.
Segmentation Analysis
By Material Type
CPVC Pipes lead the material-type segment, accounting for 47.0% of global market value in 2026, equivalent to USD 3.20 Billion. Their leadership reflects CPVC's favorable installation efficiency and corrosion resistance relative to conventional metal piping alternatives. Steel Pipes represent a significant, established material-type category. HDPE Pipes represent the fastest-growing material-type category through 2033, driven by growing preference for lightweight, corrosion-resistant piping materials.
By End Use
Commercial Buildings form the leading end-use segment, representing 58.0% of global demand in 2026, or USD 3.94 Billion, reflecting stringent commercial building fire safety regulatory requirements and substantial commercial construction activity. Residential Buildings represents the fastest-growing end-use category, propelled by expanding residential fire safety regulatory requirements and multi-family construction growth.
Regional Insights
Asia Pacific
Asia Pacific holds the largest regional share, at 36.0% of the global market in 2026, equivalent to USD 2.45 Billion. The region's dominance reflects substantial construction activity and strengthening fire safety regulatory enforcement across China, India, and Southeast Asia.
North America
North America accounts for 32.0% of the global market in 2026, valued at USD 2.18 Billion. Demand is supported by stringent fire safety building codes and sustained commercial construction activity across the United States and Canada.
Europe
Europe represents 22.0% of the global market in 2026, or USD 1.50 Billion. Growth is underpinned by established fire safety regulatory standards and steady commercial construction activity across major European markets.
Latin America
Latin America contributes 6.0% of the global market in 2026, equivalent to USD 0.41 Billion. Growth is linked to expanding construction activity and strengthening fire safety regulations in Brazil and Mexico.
Middle East & Africa
Middle East & Africa holds 4.0% of the global market in 2026, valued at USD 0.27 Billion. Growth is supported by substantial commercial construction activity across the Gulf region.
Competitive Landscape
The global fire protection system pipes market is moderately concentrated, with a mix of large diversified piping and fluid control companies and specialized fire protection material manufacturers competing for building developer and contractor adoption. Competition centers on material performance and certification compliance, installation efficiency, and the strength of relationships with fire protection contractors and building developers. Companies are increasingly differentiating through expanded HDPE and advanced material capability rather than competing on conventional steel and CPVC products alone.
Key Market Players
- Victaulic Company
- Tyco Fire Products LP
- Lubrizol Corporation
- Georg Fischer Ltd
- Aliaxis Group SA
- Mueller Water Products, Inc.
- IPEX Inc.
- Charlotte Pipe and Foundry Company
- National Pipe & Plastics, Inc.
- Watts Water Technologies, Inc.
Market Segmentation
By Material Type
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
By End Use
- Commercial Buildings
- Residential Buildings
- Others
By System Type
- Sprinkler Systems
- Standpipe Systems
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Fire Protection System Pipes Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Fire Protection System Pipes Market Outlook, 2020 - 2033
- Global Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
- Global Fire Protection System Pipes Market Outlook, by End Use, Value (US$ Mn), 2020-2033
- Commercial Buildings
- Residential Buildings
- Others
- Global Fire Protection System Pipes Market Outlook, by System Type, Value (US$ Mn), 2020-2033
- Sprinkler Systems
- Standpipe Systems
- Global Fire Protection System Pipes Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- North America Fire Protection System Pipes Market Outlook, 2020 - 2033
- North America Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
- North America Fire Protection System Pipes Market Outlook, by End Use, Value (US$ Mn), 2020-2033
- Commercial Buildings
- Residential Buildings
- Others
- North America Fire Protection System Pipes Market Outlook, by System Type, Value (US$ Mn), 2020-2033
- Sprinkler Systems
- Standpipe Systems
- North America Fire Protection System Pipes Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- U.S. Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- U.S. Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Canada Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Canada Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Canada Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- Europe Fire Protection System Pipes Market Outlook, 2020 - 2033
- Europe Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
- Europe Fire Protection System Pipes Market Outlook, by End Use, Value (US$ Mn), 2020-2033
- Commercial Buildings
- Residential Buildings
- Others
- Europe Fire Protection System Pipes Market Outlook, by System Type, Value (US$ Mn), 2020-2033
- Sprinkler Systems
- Standpipe Systems
- Europe Fire Protection System Pipes Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Germany Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Germany Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Italy Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Italy Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Italy Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- France Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- France Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- France Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- U.K. Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- U.K. Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- U.K. Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Spain Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Spain Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Spain Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Russia Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Russia Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Russia Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Rest of Europe Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Rest of Europe Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Rest of Europe Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- Asia Pacific Fire Protection System Pipes Market Outlook, 2020 - 2033
- Asia Pacific Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
- Asia Pacific Fire Protection System Pipes Market Outlook, by End Use, Value (US$ Mn), 2020-2033
- Commercial Buildings
- Residential Buildings
- Others
- Asia Pacific Fire Protection System Pipes Market Outlook, by System Type, Value (US$ Mn), 2020-2033
- Sprinkler Systems
- Standpipe Systems
- Asia Pacific Fire Protection System Pipes Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- China Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- China Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Japan Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Japan Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Japan Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- South Korea Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- South Korea Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- South Korea Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- India Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- India Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- India Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Southeast Asia Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Southeast Asia Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Southeast Asia Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Rest of SAO Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Rest of SAO Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Rest of SAO Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- Latin America Fire Protection System Pipes Market Outlook, 2020 - 2033
- Latin America Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
- Latin America Fire Protection System Pipes Market Outlook, by End Use, Value (US$ Mn), 2020-2033
- Commercial Buildings
- Residential Buildings
- Others
- Latin America Fire Protection System Pipes Market Outlook, by System Type, Value (US$ Mn), 2020-2033
- Sprinkler Systems
- Standpipe Systems
- Latin America Fire Protection System Pipes Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Brazil Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Brazil Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Mexico Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Mexico Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Mexico Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Argentina Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Argentina Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Argentina Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Rest of LATAM Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Rest of LATAM Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Rest of LATAM Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- Middle East & Africa Fire Protection System Pipes Market Outlook, 2020 - 2033
- Middle East & Africa Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
- Middle East & Africa Fire Protection System Pipes Market Outlook, by End Use, Value (US$ Mn), 2020-2033
- Commercial Buildings
- Residential Buildings
- Others
- Middle East & Africa Fire Protection System Pipes Market Outlook, by System Type, Value (US$ Mn), 2020-2033
- Sprinkler Systems
- Standpipe Systems
- Middle East & Africa Fire Protection System Pipes Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- GCC Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- GCC Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- South Africa Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- South Africa Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- South Africa Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Egypt Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Egypt Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Egypt Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Nigeria Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Nigeria Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Nigeria Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- Rest of Middle East Fire Protection System Pipes Market Outlook, by Material Type, 2020-2033
- Rest of Middle East Fire Protection System Pipes Market Outlook, by End Use, 2020-2033
- Rest of Middle East Fire Protection System Pipes Market Outlook, by System Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Fire Protection System Pipes Market Outlook, by Material Type, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Victaulic Company
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Tyco Fire Products LP
- Lubrizol Corporation
- Georg Fischer Ltd
- Aliaxis Group SA
- Mueller Water Products, Inc.
- IPEX Inc.
- Charlotte Pipe and Foundry Company
- National Pipe & Plastics, Inc.
- Watts Water Technologies, Inc.
- Victaulic Company
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Material Type
- CPVC Pipes
- Steel Pipes
- HDPE Pipes
- Others
By End Use
- Commercial Buildings
- Residential Buildings
- Others
By System Type
- Sprinkler Systems
- Standpipe Systems
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global fire protection system pipes market is valued at USD 6.80 Billion in 2026, reflecting sustained construction activity and strengthening fire safety regulations.
The market is projected to grow at a CAGR of 6.2%, reaching USD 10.36 Billion by 2033, driven by regulatory enforcement and material technology innovation.
CPVC Pipes lead with a 47.0% share in 2026, reflecting their favorable installation efficiency and corrosion resistance.
Asia Pacific leads with a 36.0% share in 2026, reflecting substantial construction activity and strengthening regulatory enforcement.
The largest opportunity lies in HDPE pipes, expanding alongside preference for lightweight, corrosion-resistant materials.
Related Reports
Industrial Belt Scale Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Industrial belt scale market to reach US$909.1 million by 2033 at 6.0% CAGR. Explore product types, accuracy classes, regional trends and key players.
Industrial Automation and Control System Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Industrial automation and control system market to reach US$289.7 billion by 2033 at 6.8% CAGR. Explore trends, segments, regions and key players.
Fabric Filter Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global fabric filter market is valued at US$11.2 billion in 2026, reaching US$16.4 billion by 2033, growing at a 5.6% CAGR
Grow Lights Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global grow lights market is valued at US$4.1 billion in 2026, reaching US$7.7 billion by 2033, growing at a 9.4% CAGR
Ground Penetrating Radar Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global ground penetrating radar market is valued at US$0.70 billion in 2026, reaching US$1.20 billion by 2033, growing at an 8.0% CAGR
3D Machine Vision Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global 3D machine vision market is valued at US$9.10 billion in 2026, reaching US$22.30 billion by 2033, growing at a 13.7% CAGR