


Renal Biomarkers Market
Renal Biomarkers Market
Renal Biomarkers Market Size and Trend Analysis
How Fast Is the Renal Biomarkers Market Growing?
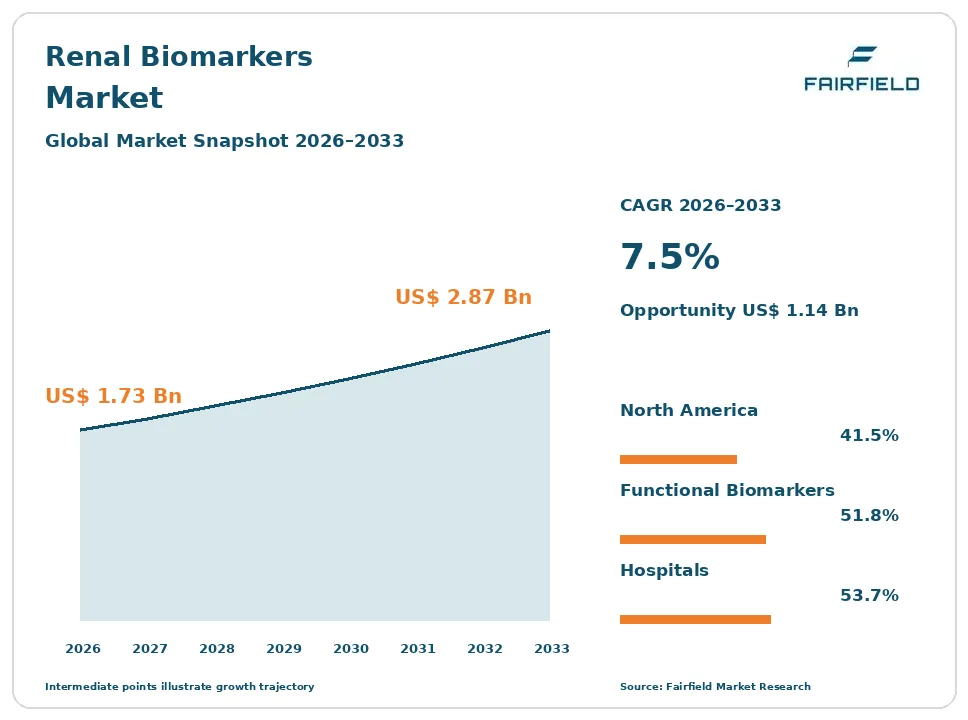
The global renal biomarkers market size is expected to be valued at US$ 1.73 billion in 2026 and projected to reach US$ 2.87 billion by 2033, growing at a CAGR of 7.5% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 6.6%, supported by rising rates of diabetes, high blood pressure, and kidney disease, along with more testing in hospitals. Three factors now drive growth: the rising burden of chronic kidney disease, the need for early detection of acute kidney injury in intensive care and surgery, and new tests that find kidney damage days before serum creatinine rises. Newer markers such as NGAL, KIM-1, and cystatin C are moving from research into routine use. The market is shifting toward automated tests that run on standard lab analyzers, AI-based risk scores that combine biomarkers with patient data, and urine tests for drug safety. Wider use of kidney-protecting drugs, such as SGLT2 inhibitors, also raises demand for early testing to find patients who could benefit.
Key Report Takeaways
- By Biomarker Type: Functional Biomarkers held 51.8% share in 2026, while Up-Regulated Proteins are projected to expand at an 8.1% CAGR through 2033, driven by adoption of NGAL and KIM-1 tests for early injury.
- By Diagnostic Technique: ELISA held 46.1% share in 2026, while CLIA is projected to expand at an 8.2% CAGR through 2033, driven by fully automated immunoassay platforms in hospital labs.
- By End User: Hospitals held 53.7% share in 2026, while Academic and Research Institutes are projected to expand at an 8.1% CAGR through 2033, driven by biomarker discovery and drug safety studies.
- By Region: North America held 41.5% share in 2026, while Asia Pacific is projected to expand at an 8.5% CAGR through 2033, driven by rising kidney disease in China and India.
Global Renal Biomarkers Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Rising burden of chronic kidney disease | High | Global | Long term (≥4 years) |
| Need for early detection of acute kidney injury | High | North America, Europe, Asia Pacific | Medium term (2-4 years) |
Two drivers carry the strongest influence on renal biomarkers demand during the forecast period.
Kidney Disease Burden Is Driving the Renal Biomarkers Market
The rising burden of chronic kidney disease is the strongest driver of the renal biomarkers market. Kidney disease affects about one in ten adults worldwide.
The mechanism is the link between kidney disease and common conditions. Diabetes and high blood pressure are the main causes of chronic kidney disease, and both are rising as populations age and obesity spreads. Many patients have no symptoms until late stages, so guidelines recommend regular testing of urine albumin and blood creatinine or cystatin C for people at risk. New treatments, including SGLT2 inhibitors and GLP-1 drugs, can slow kidney decline, which makes finding patients early more valuable. Blood tests such as Renalytix’s kidneyintelX.dkd predict who is likely to get worse. These factors increase testing volumes in primary care and specialist clinics.
Early Injury Detection Is Expanding the Renal Biomarkers Market
The need for early detection of acute kidney injury is expanding the renal biomarkers market. Acute kidney injury affects many hospital patients, especially after surgery or in intensive care.
The cause is the slow response of standard tests. Serum creatinine rises only after major damage, often two or three days late. Newer markers such as NGAL, KIM-1, and TIMP-2/IGFBP7 detect injury within hours, allowing doctors to adjust drugs, fluids, and treatment. In 2025, BioPorto made its ProNephro AKI (NGAL) test available to U.S. labs through Roche Diagnostics analyzers. Hospitals use early detection to reduce dialysis, shorten stays, and cut costs. Drug developers also use these markers to check kidney safety in trials. These trends widen use across hospital and research settings.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Limited reimbursement and clinical adoption | High | North America, Europe | Medium term (2-4 years) |
| Validation challenges and test variability | Medium | Global | Long term (≥4 years) |
Two restraints limit how quickly the renal biomarkers market grows.
Limited Reimbursement Slows the Renal Biomarkers Market
Limited reimbursement and slow clinical adoption slow the renal biomarkers market. Many new kidney tests lack clear payment from insurers.
The specific causes are cost and habit. Newer biomarker tests cost more than serum creatinine, which is cheap and widely available. Insurers often want proof that new tests improve patient outcomes, not just detection, before they pay. Many doctors remain used to creatinine and urine albumin and are unsure how to act on new results. Clinical guidelines include only a few new markers so far. Hospital labs must buy reagents and train staff for each new test. Smaller hospitals in rural areas may not offer them at all. These factors slow uptake outside large academic centers and keep volumes low, even where the clinical case for earlier testing is strong.
Validation Challenges Restrict the Renal Biomarkers Market
Validation challenges and test variability restrict the renal biomarkers market. Some biomarkers perform differently across patient groups.
The underlying causes are biological and technical. Levels of NGAL and other markers can rise with infection or inflammation, not just kidney injury, causing false alarms. Results may differ between test platforms and labs, which complicates comparisons. Many studies use small groups of patients, and large trials are expensive. Regulatory approval often covers only certain ages or settings; BioPorto’s NGAL test, for example, is cleared for children and young adults in the United States, and an adult version is still being pursued. Doctors also disagree on the best cut-off values for some markers. Building the evidence needed for each new use case can take years. These factors delay wider approvals and slow growth.
Market Opportunities
AI-Based Risk Scores Open a High-Value Revenue Pool
AI-based risk scores that combine biomarkers with patient data open a high-value revenue pool in the renal biomarkers market. These tools predict which patients will lose kidney function.
Diagnostic companies with data and software skills can capture this opportunity. Renalytix partnered with Tempus AI in 2025 to widen access to its kidneyintelX.dkd test across U.S. health systems. Roche received European approval for its AI-based Kidney Klinrisk algorithm in 2025. These tools help doctors choose who needs new drugs or specialist care. Insurers may pay for tests that reduce dialysis costs. Results delivered into electronic health records make adoption easier. Drug makers selling kidney-protecting medicines may also support testing, since finding at-risk patients early grows their market. Large health systems can use these tools to manage whole patient populations.
Drug Safety Testing Creates a Research Revenue Pool
Drug safety testing creates a research revenue pool in the renal biomarkers market. Drug developers must check that new medicines do not harm the kidneys.
Test makers and contract labs can capture this opportunity. Urine biomarkers detect drug-induced kidney injury earlier than standard tests, helping companies stop risky drugs sooner. Regulators in the United States and Europe are working to qualify biomarker panels for this use. Cancer drugs, antibiotics, and contrast agents used in imaging often harm the kidneys. Growing drug pipelines in oncology and cell therapy increase testing needs. Academic and research institutes are also buying more assays for discovery work. Contract research organizations add demand by running kidney safety panels for drug companies. Test makers that win regulatory qualification can become the standard for these studies across the industry.
Segment Analysis
By Biomarker Type: Functional Biomarkers Lead While Up-Regulated Proteins Grow Fastest
Functional Biomarkers held 51.8% share in 2026. This group includes serum creatinine, cystatin C, and urine albumin, which measure how well the kidneys filter blood. They are part of routine blood and urine tests worldwide, and guidelines increasingly recommend cystatin C for more accurate results. Roche, Abbott Laboratories, and Siemens Healthineers supply these tests on high-volume analyzers.
Up-Regulated Proteins are the fastest-growing biomarker type, expanding at an 8.1% CAGR through 2033. NGAL, KIM-1, and IL-18 rise quickly when kidney cells are damaged, giving an early warning of acute kidney injury. New approvals and automated versions make them easier for hospitals to use. For the market, this growth adds higher-value tests.
By Diagnostic Technique: ELISA Leads While CLIA Grows Fastest
ELISA held 46.1% share in 2026. Enzyme-linked immunosorbent assays are widely used in research and many clinical labs because they are accurate and flexible. Thermo Fisher Scientific, Bio-Rad Laboratories, and R&D Systems sell ELISA kits for many kidney markers. ELISA remains the main tool for biomarker discovery.
CLIA is the fastest-growing technique, expanding at an 8.2% CAGR through 2033. Chemiluminescent immunoassays run on automated analyzers that deliver results quickly and handle large numbers of samples. Hospital labs prefer automation to reduce staff time, and the BioPorto NGAL test now runs on Roche analyzers. PETIA and LC-MS serve specific uses such as cystatin C and research. For the market, CLIA growth supports routine clinical use.
By End User: Hospitals Lead While Academic and Research Institutes Grow Fastest
Hospitals held 53.7% share in 2026. Hospitals test patients in intensive care, emergency rooms, and surgery for acute kidney injury, and they monitor patients with chronic kidney disease. Large hospital labs run most kidney biomarker tests on automated analyzers, often around the clock for urgent cases.
Academic and Research Institutes are the fastest-growing end user, expanding at an 8.1% CAGR through 2033. Universities and research centers study new markers, run clinical trials, and test drug safety. Government and pharma funding for kidney research is rising, and regulators want better urine biomarkers for drug-induced kidney injury. Diagnostic laboratories also grow as outpatient and primary care testing for kidney disease expands. For the market, research demand supports future test approvals.
Geography Analysis
Which Region Is Leading the Renal Biomarkers Market?
North America is leading the renal biomarkers market with a 41.5% share in 2026. The United States has a large number of patients with diabetes and chronic kidney disease, along with well-funded hospitals and labs. Abbott Laboratories, Thermo Fisher Scientific, Renalytix, and Quest Diagnostics are active here. The U.S. Food and Drug Administration has cleared several new kidney tests. Canada adds demand through public health programs. Medicare covers many kidney patients, which shapes payment decisions for new tests. Key barriers include reimbursement gaps. One change shaping the region is AI-based risk testing linked to electronic health records.
Europe Builds the Renal Biomarkers Market Through Guideline Adoption
Europe holds about 26.9% of the renal biomarkers market. Germany, the United Kingdom, France, Italy, and Spain have strong hospital lab networks and research programs. Roche, Siemens Healthineers, bioMérieux, Randox, and SphingoTec are based in the region. European guidelines recommend cystatin C testing in more cases. Denmark hosts BioPorto, a specialist in NGAL testing, and the Netherlands and Sweden run large kidney research studies. Key barriers include budget limits in public health systems and slow reimbursement decisions. One opportunity is AI-based risk tools approved under European rules and linked to national screening.
Which Region Is Growing Fastest in the Renal Biomarkers Market?
Asia Pacific is growing fastest in the renal biomarkers market at an 8.5% CAGR through 2033. China and India have large and growing numbers of people with diabetes and kidney disease. Japan and South Korea have aging populations and advanced hospital labs, and Sysmex and Fujirebio supply tests from Japan. Australia funds kidney screening programs. Hospital spending is rising quickly across the region, and local test makers in China offer lower-cost kits. Key barriers include cost in rural areas and limited insurance coverage. One change shaping the region is wider testing in China under national chronic disease plans.
Latin America Grows the Renal Biomarkers Market Through Diabetes Testing
Latin America is a growing renal biomarkers market. Brazil and Mexico have high rates of diabetes and chronic kidney disease, and Mexico has some of the highest kidney disease death rates in the world. Argentina, Colombia, and Chile are expanding lab testing in public and private hospitals. Private labs are adopting automated analyzers, and global companies are expanding distribution in Brazil and Mexico. Dialysis costs push governments to support earlier testing. Key barriers include limited public budgets and uneven access to specialist care. One opportunity is screening programs for people with diabetes run through public clinics and pharmacies.
Middle East & Africa Expands the Renal Biomarkers Market Through Healthcare Investment
Middle East & Africa is an emerging renal biomarkers market. Saudi Arabia and the United Arab Emirates have high diabetes rates and are investing in hospitals and labs. Israel has strong research programs. South Africa, Egypt, and Nigeria face rising kidney disease but have limited testing. Qatar and Kuwait fund chronic disease programs. Many new hospitals in Saudi Arabia are buying automated lab systems from global suppliers. Key barriers include cost, few specialist labs, and limited nephrology staff in Middle East & Africa. One opportunity is automated testing in new hospitals and diabetes clinics across the region.
Competitive Landscape
The renal biomarkers market is moderately concentrated. F. Hoffmann-La Roche, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, bioMérieux, and Beckman Coulter (part of Danaher) supply most routine kidney tests on their analyzers. Specialists such as BioPorto, Randox Laboratories, SphingoTec, Renalytix, and Bio-Rad Laboratories focus on newer markers and risk tools.
Companies compete on test accuracy, speed, automation, the number of analyzers in use, and regulatory approvals. Large diagnostic firms benefit from installed analyzers in hospitals, which make it easy to add new tests. Smaller firms often partner with them to reach labs, as BioPorto did with Roche Diagnostics. Software and AI tools are becoming a new area of competition, and companies with strong clinical data have an advantage with insurers. Lab service providers such as Quest Diagnostics also shape demand through testing volumes.
Strategic moves show how competition is changing. In August 2025, BioPorto launched its ProNephro AKI (NGAL) test in the U.S. through Roche Diagnostics. In September 2025, Renalytix partnered with Tempus AI. In October 2025, Roche gained a CE mark for its Kidney Klinrisk algorithm. In March 2026, BioPorto filed an FDA pre-submission for an adult NGAL test. These moves show competition shifting toward early detection and AI tools.
Three themes shape vendor strategy. First, companies are automating new biomarker tests. Second, they are adding AI-based risk scores. Third, they are seeking wider approvals for adults and new settings.
Renal Biomarkers Market Industry Leaders
- F. Hoffmann-La Roche
- Abbott Laboratories
- Siemens Healthineers
- Thermo Fisher Scientific
- bioMérieux
Recent Industry Developments
- March 2026: BioPorto submitted an FDA pre-submission package for its adult urine NGAL test - moves toward wider U.S. use for acute kidney injury.
- October 2025: Roche received a CE mark for its AI-based Kidney Klinrisk algorithm - adds AI risk prediction for chronic kidney disease in Europe.
- September 2025: Renalytix signed an agreement with Tempus AI to expand access to its kidneyintelX.dkd blood test - widens U.S. use of prognostic kidney testing.
- August 2025: BioPorto made its ProNephro AKI (NGAL) test available to U.S. labs on Roche cobas c 501 analyzers - brings early detection of pediatric kidney injury to hospitals.
Companies Covered in the Report
- F. Hoffmann-La Roche
- Abbott Laboratories
- Siemens Healthineers
- Thermo Fisher Scientific
- bioMérieux
- Beckman Coulter
- BioPorto
- Randox Laboratories
- SphingoTec
- Renalytix
- Bio-Rad Laboratories
- Sysmex
Renal Biomarkers Market Report Scope
This report covers biomarkers used to detect and monitor kidney disease and injury, including functional biomarkers and up-regulated proteins, tested by ELISA, PETIA, colorimetric assay, CLIA, and LC-MS, in hospitals, diagnostic laboratories, and academic and research institutes. It includes test kits and reagents. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
Biomarker Type
- Functional Biomarkers
- Up-Regulated Proteins
- Others
Diagnostic Technique
- ELISA
- PETIA
- Colorimetric Assay
- CLIA
- LC-MS
End User
- Hospitals
- Diagnostic Laboratories
- Academic and Research Institutes
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the renal biomarkers market in 2026?
The renal biomarkers market is valued at US$ 1.73 billion in 2026, led by functional biomarkers and hospital testing.
What is the renal biomarkers market forecast to 2033?
The market is projected to reach US$ 2.87 billion by 2033, growing at a 7.5% CAGR and adding US$ 1.14 billion.
Which biomarker type is growing fastest in the renal biomarkers market?
Up-regulated proteins are growing fastest at an 8.1% CAGR through 2033, driven by NGAL and KIM-1 tests for early kidney injury.
Which region is growing fastest in the renal biomarkers market?
Asia Pacific is growing fastest at an 8.5% CAGR through 2033, driven by rising diabetes and kidney disease in China and India.
Which region holds the largest renal biomarkers market share?
North America holds the largest share at 41.5% in 2026, supported by high testing volumes and new FDA-cleared kidney tests.
1. Executive Summary
1.1. Global Renal Biomarkers Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Kidney Disease Burden Is Driving the Renal Biomarkers Market
2.3.1.2. Early Injury Detection Is Expanding the Renal Biomarkers Market
2.3.2. Restraints
2.3.2.1. Limited Reimbursement Slows the Renal Biomarkers Market
2.3.2.2. Validation Challenges Restrict the Renal Biomarkers Market
2.3.3. Market Opportunities
2.3.3.1. AI-Based Risk Scores Open a High-Value Revenue Pool
2.3.3.2. Drug Safety Testing Creates a Research Revenue Pool
3. Global Renal Biomarkers Market Outlook, 2020-2033
3.1. Global Renal Biomarkers Market Outlook, by Biomarker Type, Value (US$ Billion), 2020-2033
3.1.1. Functional Biomarkers
3.1.2. Up-Regulated Proteins
3.1.3. Others
3.2. Global Renal Biomarkers Market Outlook, by Diagnostic Technique, Value (US$ Billion), 2020-2033
3.2.1. ELISA
3.2.2. PETIA
3.2.3. Colorimetric Assay
3.2.4. CLIA
3.2.5. LC-MS
3.3. Global Renal Biomarkers Market Outlook, by End User, Value (US$ Billion), 2020-2033
3.3.1. Hospitals
3.3.2. Diagnostic Laboratories
3.3.3. Academic and Research Institutes
3.4. Global Renal Biomarkers Market Outlook, by Region, Value (US$ Billion), 2020-2033
3.4.1. North America
3.4.2. Europe
3.4.3. Asia Pacific
3.4.4. Latin America
3.4.5. Middle East & Africa
4. North America Renal Biomarkers Market Outlook, 2020-2033
4.1. North America Renal Biomarkers Market Outlook, by Biomarker Type, Value (US$ Billion), 2020-2033
4.1.1. Functional Biomarkers
4.1.2. Up-Regulated Proteins
4.1.3. Others
4.2. North America Renal Biomarkers Market Outlook, by Diagnostic Technique, Value (US$ Billion), 2020-2033
4.2.1. ELISA
4.2.2. PETIA
4.2.3. Colorimetric Assay
4.2.4. CLIA
4.2.5. LC-MS
4.3. North America Renal Biomarkers Market Outlook, by End User, Value (US$ Billion), 2020-2033
4.3.1. Hospitals
4.3.2. Diagnostic Laboratories
4.3.3. Academic and Research Institutes
4.4. North America Renal Biomarkers Market Outlook, by Country, Value (US$ Billion), 2020-2033
4.4.1. United States Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
4.4.2. United States Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
4.4.3. United States Renal Biomarkers Market Outlook, by End User, 2020-2033
4.4.4. Canada Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
4.4.5. Canada Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
4.4.6. Canada Renal Biomarkers Market Outlook, by End User, 2020-2033
5. Europe Renal Biomarkers Market Outlook, 2020-2033
5.1. Europe Renal Biomarkers Market Outlook, by Biomarker Type, Value (US$ Billion), 2020-2033
5.1.1. Functional Biomarkers
5.1.2. Up-Regulated Proteins
5.1.3. Others
5.2. Europe Renal Biomarkers Market Outlook, by Diagnostic Technique, Value (US$ Billion), 2020-2033
5.2.1. ELISA
5.2.2. PETIA
5.2.3. Colorimetric Assay
5.2.4. CLIA
5.2.5. LC-MS
5.3. Europe Renal Biomarkers Market Outlook, by End User, Value (US$ Billion), 2020-2033
5.3.1. Hospitals
5.3.2. Diagnostic Laboratories
5.3.3. Academic and Research Institutes
5.4. Europe Renal Biomarkers Market Outlook, by Country, Value (US$ Billion), 2020-2033
5.4.1. Germany Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.2. Germany Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.3. Germany Renal Biomarkers Market Outlook, by End User, 2020-2033
5.4.4. United Kingdom Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.5. United Kingdom Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.6. United Kingdom Renal Biomarkers Market Outlook, by End User, 2020-2033
5.4.7. France Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.8. France Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.9. France Renal Biomarkers Market Outlook, by End User, 2020-2033
5.4.10. Italy Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.11. Italy Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.12. Italy Renal Biomarkers Market Outlook, by End User, 2020-2033
5.4.13. Spain Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.14. Spain Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.15. Spain Renal Biomarkers Market Outlook, by End User, 2020-2033
5.4.16. Denmark Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.17. Denmark Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.18. Denmark Renal Biomarkers Market Outlook, by End User, 2020-2033
5.4.19. Netherlands Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.20. Netherlands Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.21. Netherlands Renal Biomarkers Market Outlook, by End User, 2020-2033
5.4.22. Sweden Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
5.4.23. Sweden Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
5.4.24. Sweden Renal Biomarkers Market Outlook, by End User, 2020-2033
6. Asia Pacific Renal Biomarkers Market Outlook, 2020-2033
6.1. Asia Pacific Renal Biomarkers Market Outlook, by Biomarker Type, Value (US$ Billion), 2020-2033
6.1.1. Functional Biomarkers
6.1.2. Up-Regulated Proteins
6.1.3. Others
6.2. Asia Pacific Renal Biomarkers Market Outlook, by Diagnostic Technique, Value (US$ Billion), 2020-2033
6.2.1. ELISA
6.2.2. PETIA
6.2.3. Colorimetric Assay
6.2.4. CLIA
6.2.5. LC-MS
6.3. Asia Pacific Renal Biomarkers Market Outlook, by End User, Value (US$ Billion), 2020-2033
6.3.1. Hospitals
6.3.2. Diagnostic Laboratories
6.3.3. Academic and Research Institutes
6.4. Asia Pacific Renal Biomarkers Market Outlook, by Country, Value (US$ Billion), 2020-2033
6.4.1. China Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
6.4.2. China Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
6.4.3. China Renal Biomarkers Market Outlook, by End User, 2020-2033
6.4.4. India Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
6.4.5. India Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
6.4.6. India Renal Biomarkers Market Outlook, by End User, 2020-2033
6.4.7. Japan Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
6.4.8. Japan Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
6.4.9. Japan Renal Biomarkers Market Outlook, by End User, 2020-2033
6.4.10. South Korea Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
6.4.11. South Korea Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
6.4.12. South Korea Renal Biomarkers Market Outlook, by End User, 2020-2033
6.4.13. Australia Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
6.4.14. Australia Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
6.4.15. Australia Renal Biomarkers Market Outlook, by End User, 2020-2033
7. Latin America Renal Biomarkers Market Outlook, 2020-2033
7.1. Latin America Renal Biomarkers Market Outlook, by Biomarker Type, Value (US$ Billion), 2020-2033
7.1.1. Functional Biomarkers
7.1.2. Up-Regulated Proteins
7.1.3. Others
7.2. Latin America Renal Biomarkers Market Outlook, by Diagnostic Technique, Value (US$ Billion), 2020-2033
7.2.1. ELISA
7.2.2. PETIA
7.2.3. Colorimetric Assay
7.2.4. CLIA
7.2.5. LC-MS
7.3. Latin America Renal Biomarkers Market Outlook, by End User, Value (US$ Billion), 2020-2033
7.3.1. Hospitals
7.3.2. Diagnostic Laboratories
7.3.3. Academic and Research Institutes
7.4. Latin America Renal Biomarkers Market Outlook, by Country, Value (US$ Billion), 2020-2033
7.4.1. Brazil Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
7.4.2. Brazil Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
7.4.3. Brazil Renal Biomarkers Market Outlook, by End User, 2020-2033
7.4.4. Mexico Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
7.4.5. Mexico Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
7.4.6. Mexico Renal Biomarkers Market Outlook, by End User, 2020-2033
7.4.7. Argentina Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
7.4.8. Argentina Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
7.4.9. Argentina Renal Biomarkers Market Outlook, by End User, 2020-2033
7.4.10. Colombia Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
7.4.11. Colombia Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
7.4.12. Colombia Renal Biomarkers Market Outlook, by End User, 2020-2033
7.4.13. Chile Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
7.4.14. Chile Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
7.4.15. Chile Renal Biomarkers Market Outlook, by End User, 2020-2033
8. Middle East & Africa Renal Biomarkers Market Outlook, 2020-2033
8.1. Middle East & Africa Renal Biomarkers Market Outlook, by Biomarker Type, Value (US$ Billion), 2020-2033
8.1.1. Functional Biomarkers
8.1.2. Up-Regulated Proteins
8.1.3. Others
8.2. Middle East & Africa Renal Biomarkers Market Outlook, by Diagnostic Technique, Value (US$ Billion), 2020-2033
8.2.1. ELISA
8.2.2. PETIA
8.2.3. Colorimetric Assay
8.2.4. CLIA
8.2.5. LC-MS
8.3. Middle East & Africa Renal Biomarkers Market Outlook, by End User, Value (US$ Billion), 2020-2033
8.3.1. Hospitals
8.3.2. Diagnostic Laboratories
8.3.3. Academic and Research Institutes
8.4. Middle East & Africa Renal Biomarkers Market Outlook, by Country, Value (US$ Billion), 2020-2033
8.4.1. Saudi Arabia Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.2. Saudi Arabia Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.3. Saudi Arabia Renal Biomarkers Market Outlook, by End User, 2020-2033
8.4.4. United Arab Emirates Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.5. United Arab Emirates Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.6. United Arab Emirates Renal Biomarkers Market Outlook, by End User, 2020-2033
8.4.7. Israel Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.8. Israel Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.9. Israel Renal Biomarkers Market Outlook, by End User, 2020-2033
8.4.10. South Africa Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.11. South Africa Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.12. South Africa Renal Biomarkers Market Outlook, by End User, 2020-2033
8.4.13. Egypt Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.14. Egypt Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.15. Egypt Renal Biomarkers Market Outlook, by End User, 2020-2033
8.4.16. Nigeria Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.17. Nigeria Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.18. Nigeria Renal Biomarkers Market Outlook, by End User, 2020-2033
8.4.19. Qatar Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.20. Qatar Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.21. Qatar Renal Biomarkers Market Outlook, by End User, 2020-2033
8.4.22. Kuwait Renal Biomarkers Market Outlook, by Biomarker Type, 2020-2033
8.4.23. Kuwait Renal Biomarkers Market Outlook, by Diagnostic Technique, 2020-2033
8.4.24. Kuwait Renal Biomarkers Market Outlook, by End User, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. F. Hoffmann-La Roche
9.5.2. Abbott Laboratories
9.5.3. Siemens Healthineers
9.5.4. Thermo Fisher Scientific
9.5.5. bioMérieux
9.5.6. Beckman Coulter
9.5.7. BioPorto
9.5.8. Randox Laboratories
9.5.9. SphingoTec
9.5.10. Renalytix
9.5.11. Bio-Rad Laboratories
9.5.12. Sysmex
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Biomarker Type | Functional Biomarkers, Up-Regulated Proteins, Others |
| Diagnostic Technique | ELISA, PETIA, Colorimetric Assay, CLIA, LC-MS |
| End User | Hospitals, Diagnostic Laboratories, Academic and Research Institutes |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The renal biomarkers market is valued at US$ 1.73 billion in 2026, led by functional biomarkers and hospital testing.
The market is projected to reach US$ 2.87 billion by 2033, growing at a 7.5% CAGR and adding US$ 1.14 billion.
Up-regulated proteins are growing fastest at an 8.1% CAGR through 2033, driven by NGAL and KIM-1 tests for early kidney injury.
Asia Pacific is growing fastest at an 8.5% CAGR through 2033, driven by rising diabetes and kidney disease in China and India.
North America holds the largest share at 41.5% in 2026, supported by high testing volumes and new FDA-cleared kidney tests.
Related Reports
Omics-Based Clinical Trials Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Omics-based clinical trials market to grow from US$38.32 Bn in 2026 to US$65.67 Bn by 2033 at 8.0% CAGR. Explore trial phases, indications and regions.
Ocular Hypertension Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Ocular hypertension market to reach US$ 8.05 billion by 2033 at an 8.2% CAGR. Explore drug classes, delivery modes, pharmacy channels and regional trends.
Obesity GLP-1 Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Obesity GLP-1 market to reach US$ 65.20 billion by 2033 at a 13.1% CAGR. Explore drugs, administration routes, pharmacy channels and regional trends.
Upstream Bioprocessing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Upstream bioprocessing market to reach US$ 92.23 billion by 2033 at a 14.3% CAGR. Explore products, use types, manufacturing modes and regional trends.
Personalized Cancer Vaccine Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Personalized cancer vaccine market to reach US$ 16.57 billion by 2033 at an 18.7% CAGR. Explore vaccine types, cancer types and regional trends.
PEGylated Proteins Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
PEGylated proteins market to reach US$ 4.58 billion by 2033 at a 10.9% CAGR. Explore products, protein types, applications and regional trends.